

The Wholesale Electricity Market
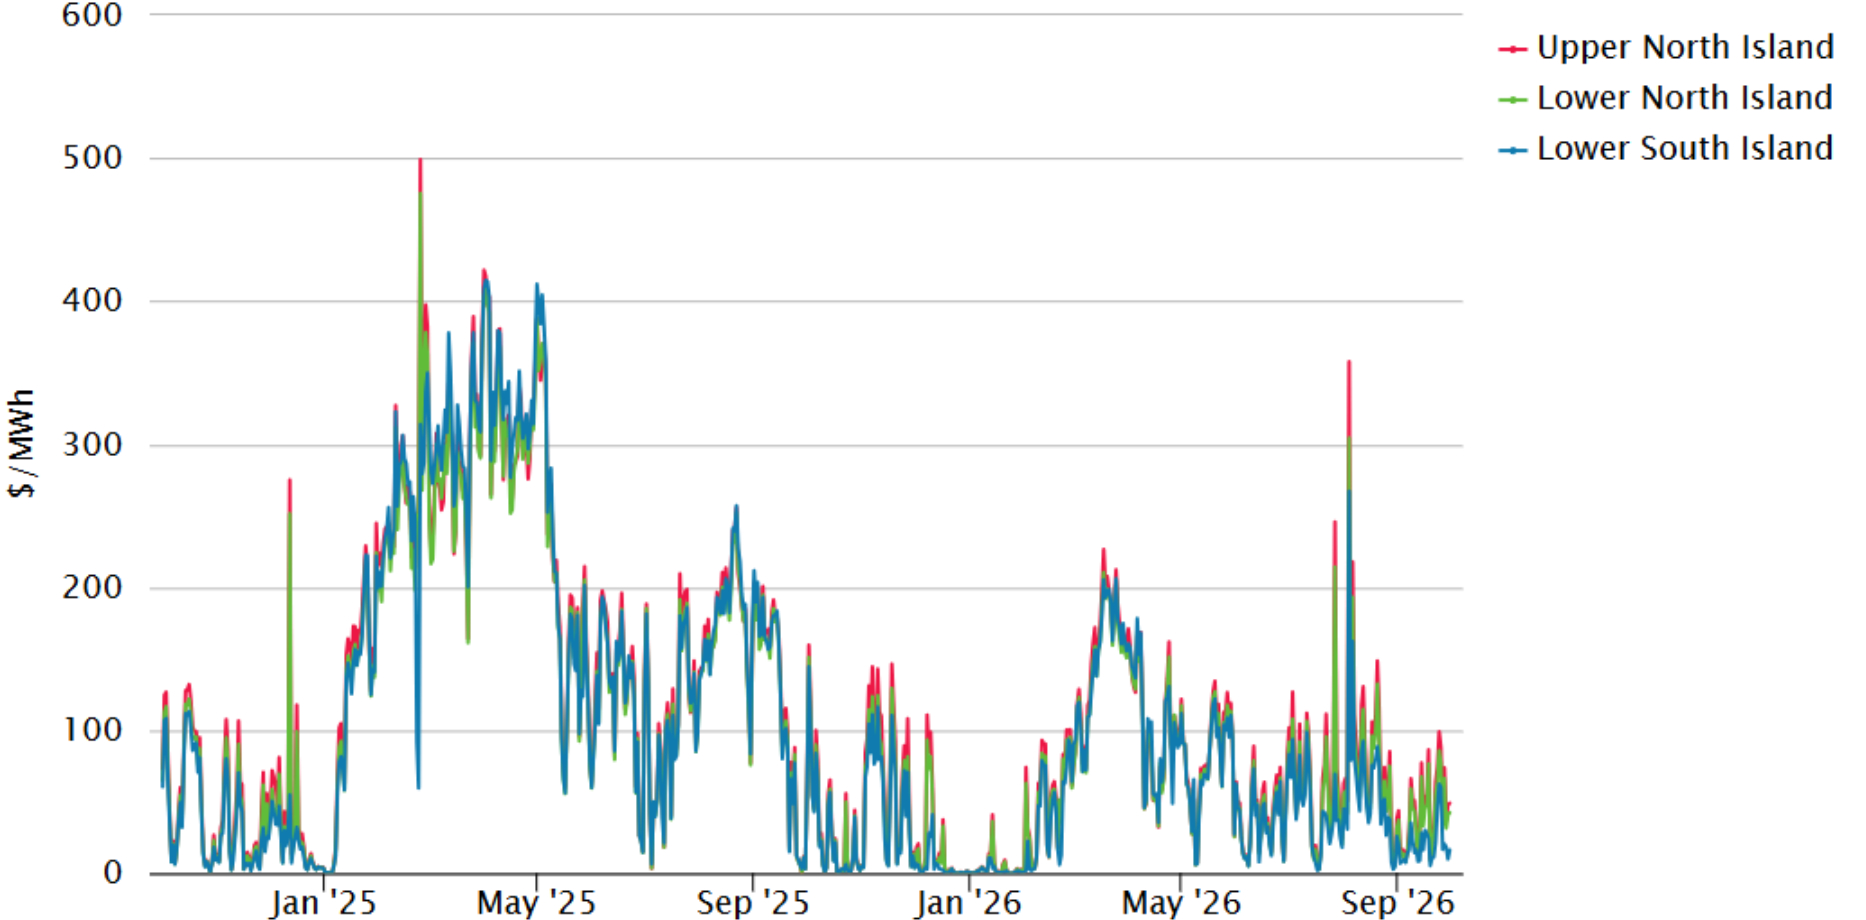
Spot prices in the wholesale electricity market decreased in September. Average spot prices for the month ranged from $20 in the lower South Island (down from $61.1 in August), to $44.2 in the upper North Island ($89.3 in August).

The following chart shows average weekly spot prices over the last 2 years. Recent low prices can be clearly seen to the right.
Electricity Demand
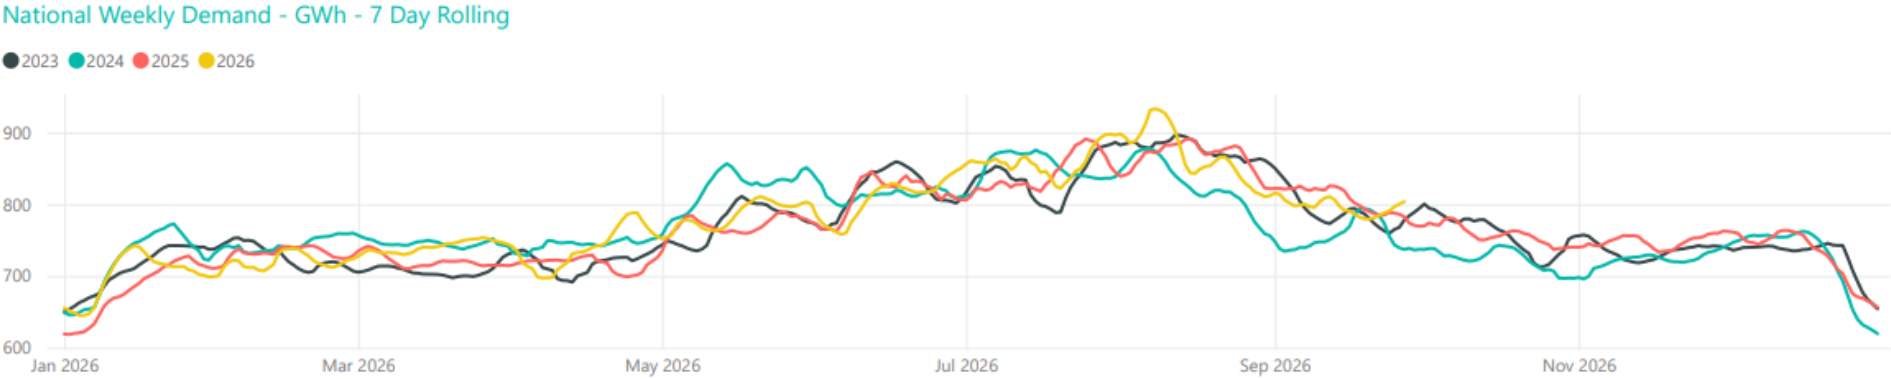
Demand started to taper off as we headed into the milder spring months, however it remained at the upper end of the range observed over the past few years, as shown in the following chart.
Electricity Generation Mix
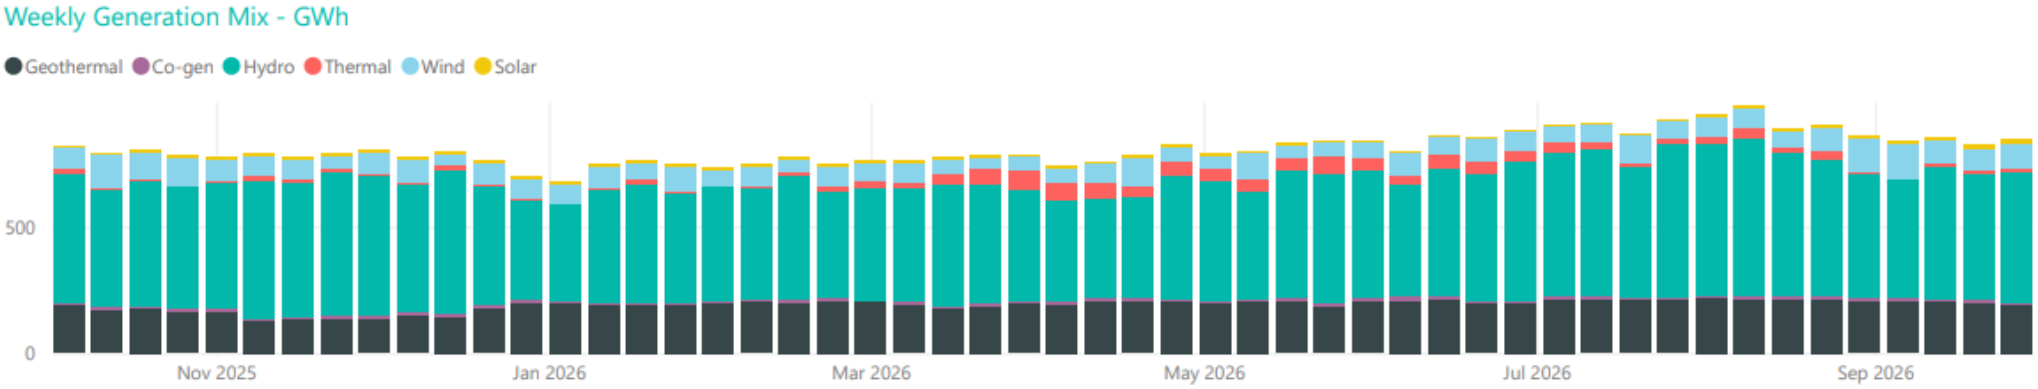
Hydro generation was able to back off slightly because demand fell and additional wind capacity entered the system. Thermal generation remained low.
HVDC Transfer
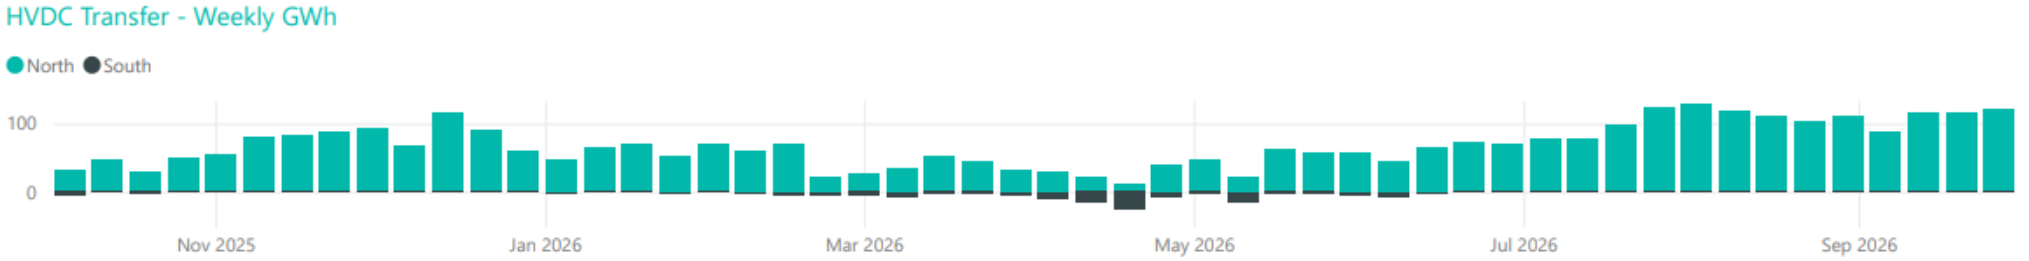
Power transfers over the HVDC link connecting the North and South Islands provide an indication of both the islands’ relative hydro positions and their reliance on thermal generation to meet demand. High northward flows tend to indicate a strong South Island hydro position, whereas southward flows indicate greater reliance on thermal generation.
Northward transfer stayed high throughout September as SI inflows remained strong. There were minimal southward transfers throughout the month.
The Electricity Futures Market
The futures market provides an indication of where market participants expect spot prices to move. Futures prices are based on actual trades between participants looking to hedge their positions (as both buyers and sellers) into the future against potential spot market volatility. Futures prices also provide a useful indication of the likely direction of retail contract prices.
The following graph shows futures prices for calendar years 2025 to 2029 at Otahuhu (Auckland) for the last 5 years.
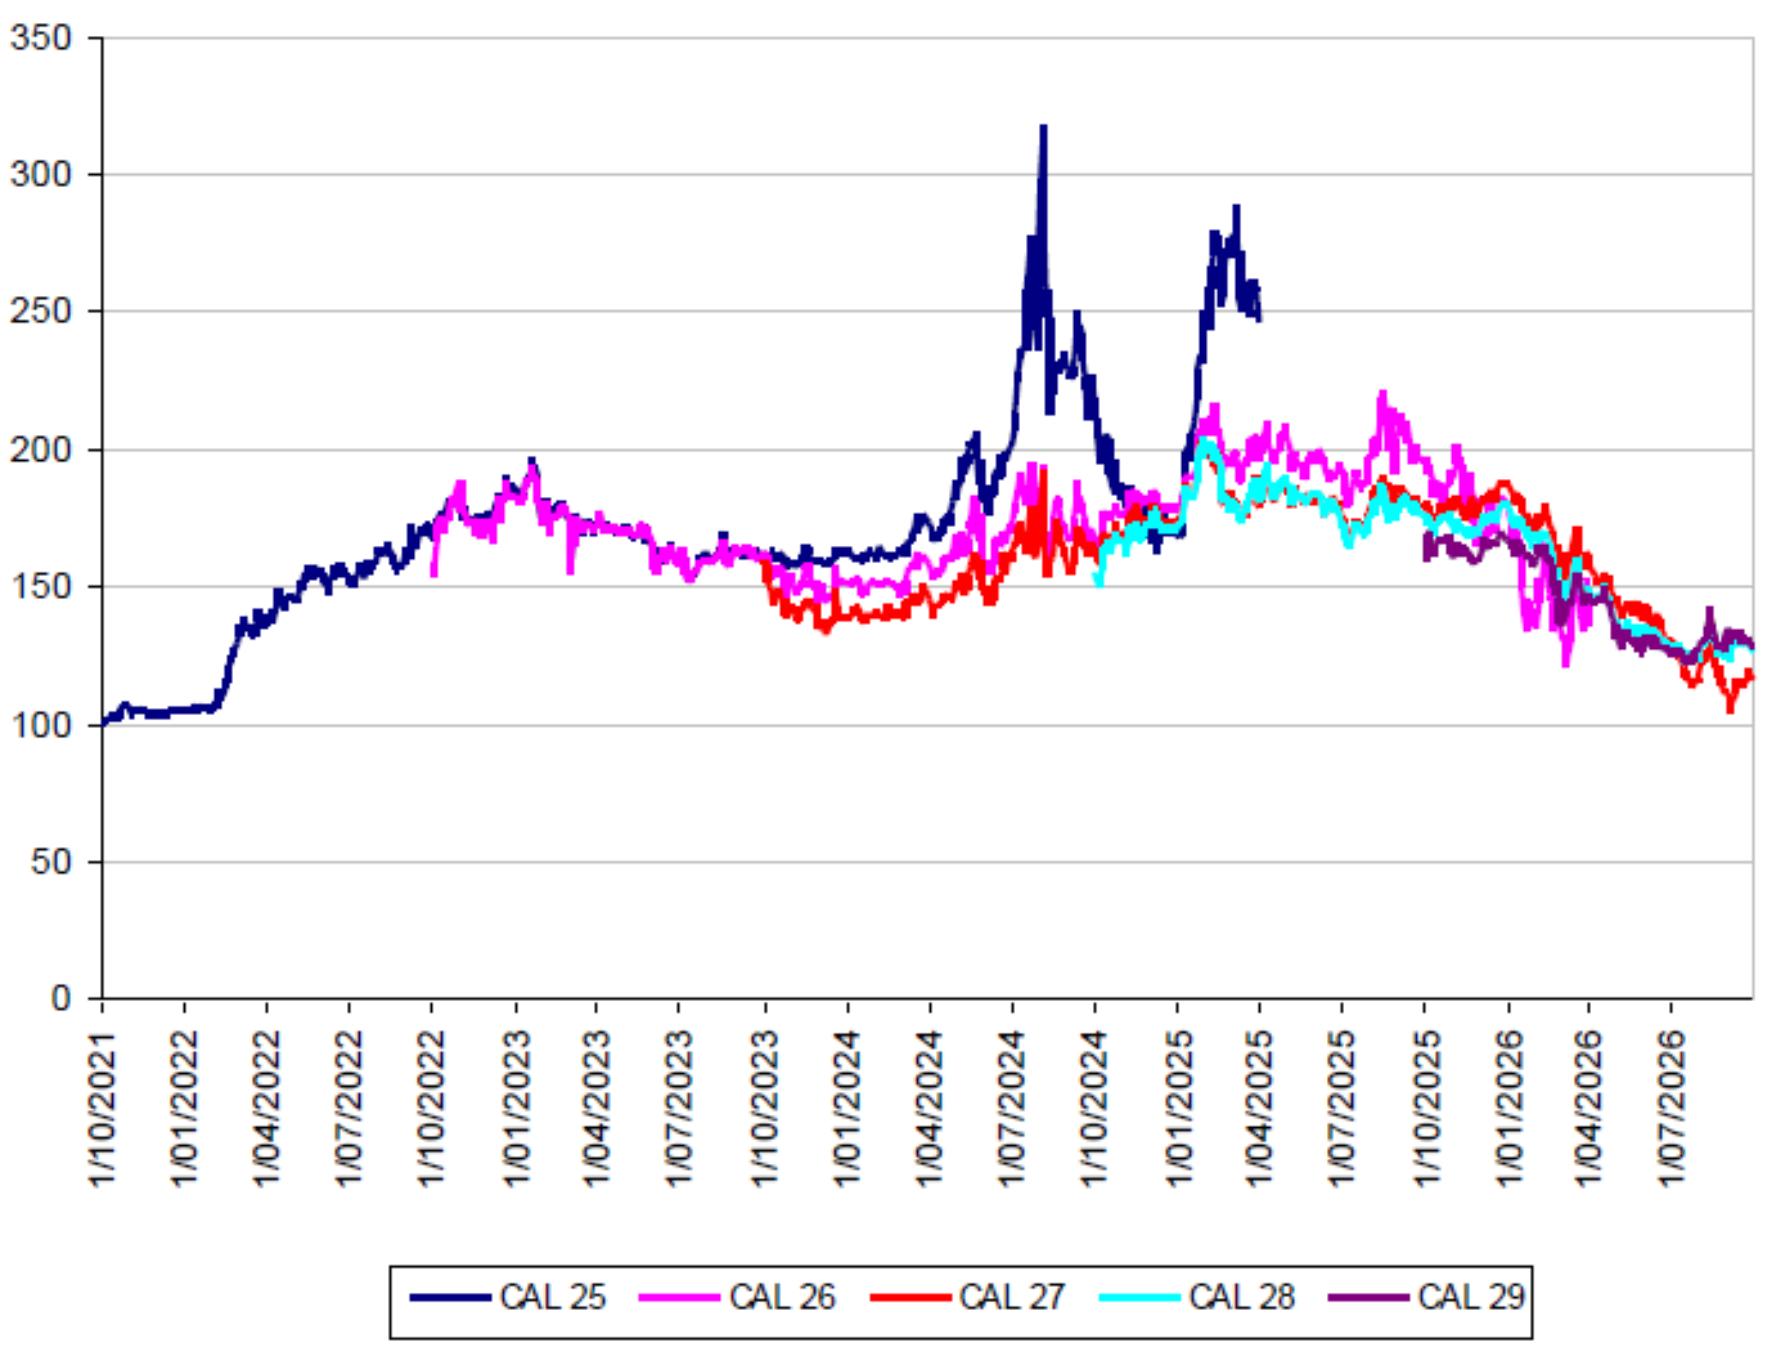
Note that $200/MWh equates to 20c/kWh.
Forward prices increased for 2027 but decreased for the later calendar years during September. CAL 2027 increased 5% ending the month at $117/MWh. CY 2028 decreased by 4% to $127/MWh, while CY 2029 decreased by 5% to $128/MWh.
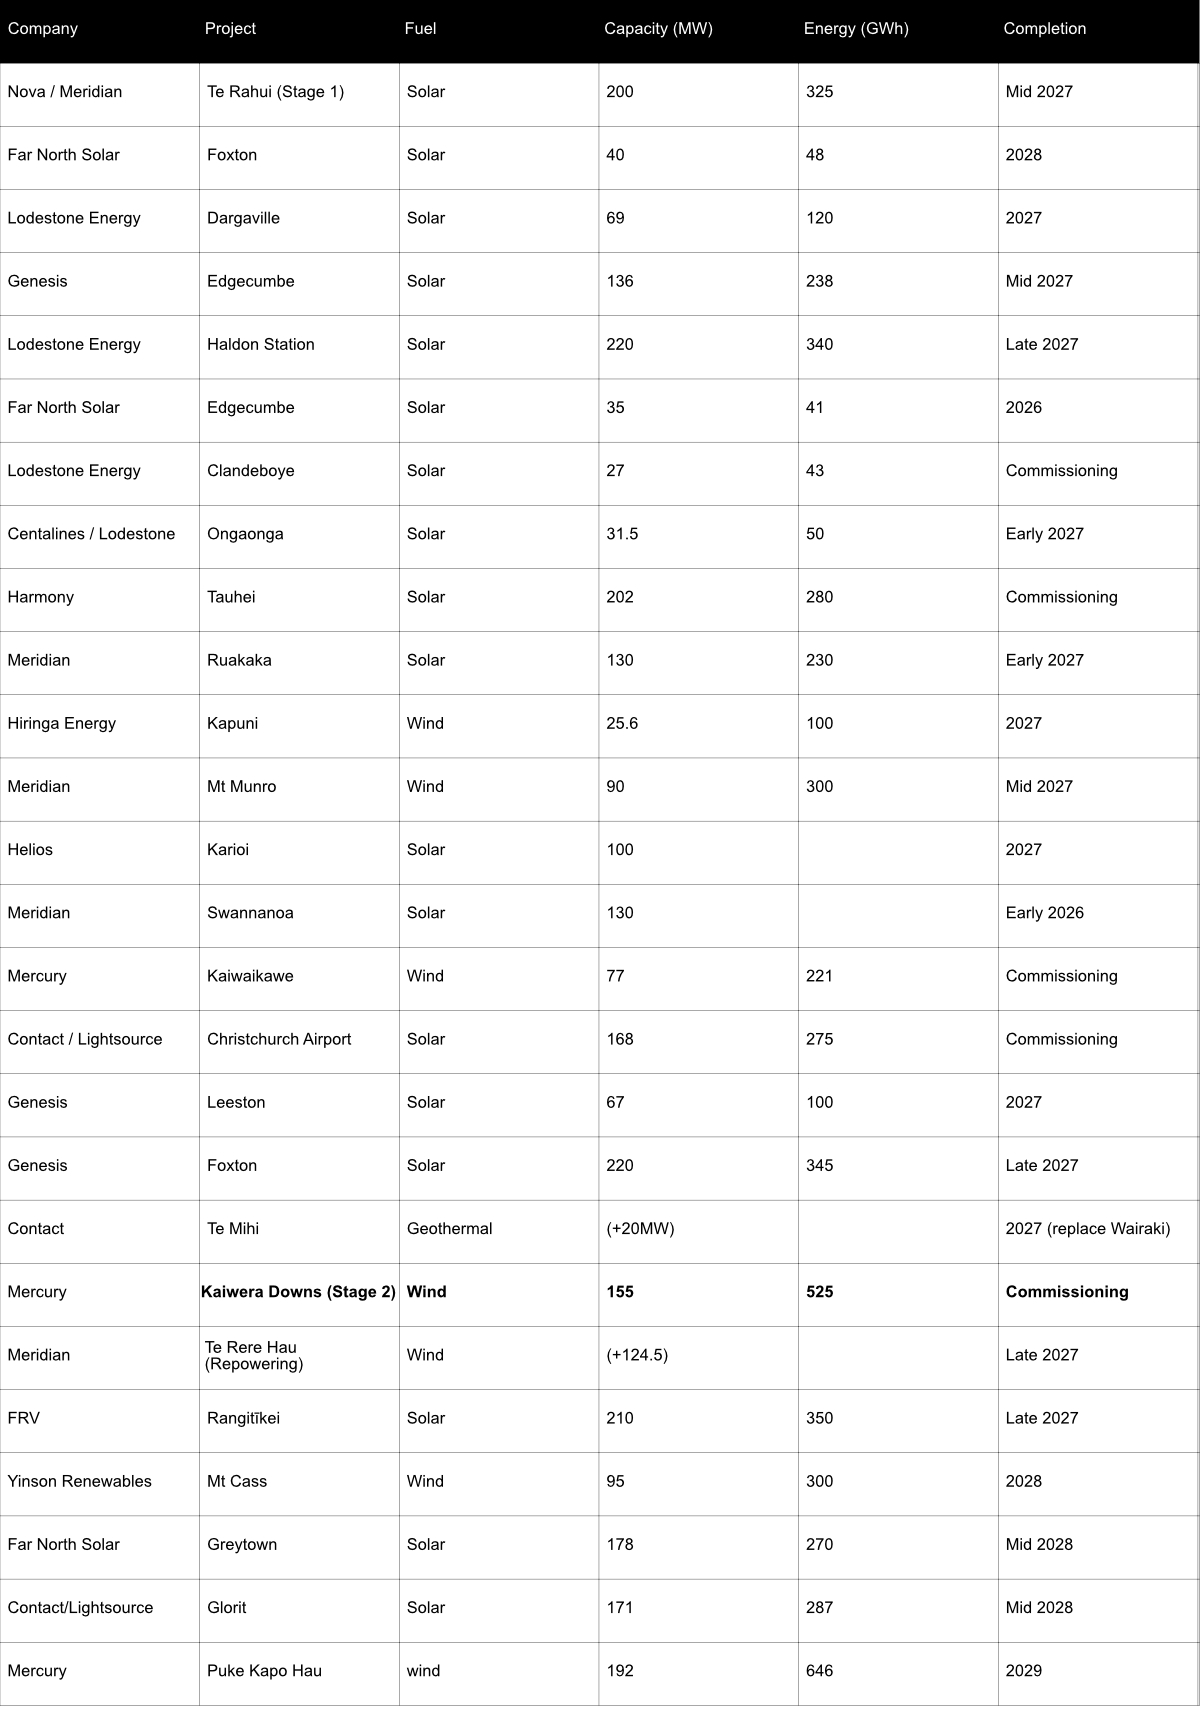
Known new generation projects are shown below, with additions, removals and changes highlighted in bold.
Hydro Storage
South Island inflows were again well above average throughout September, while North Island inflows were well below average, as shown below.
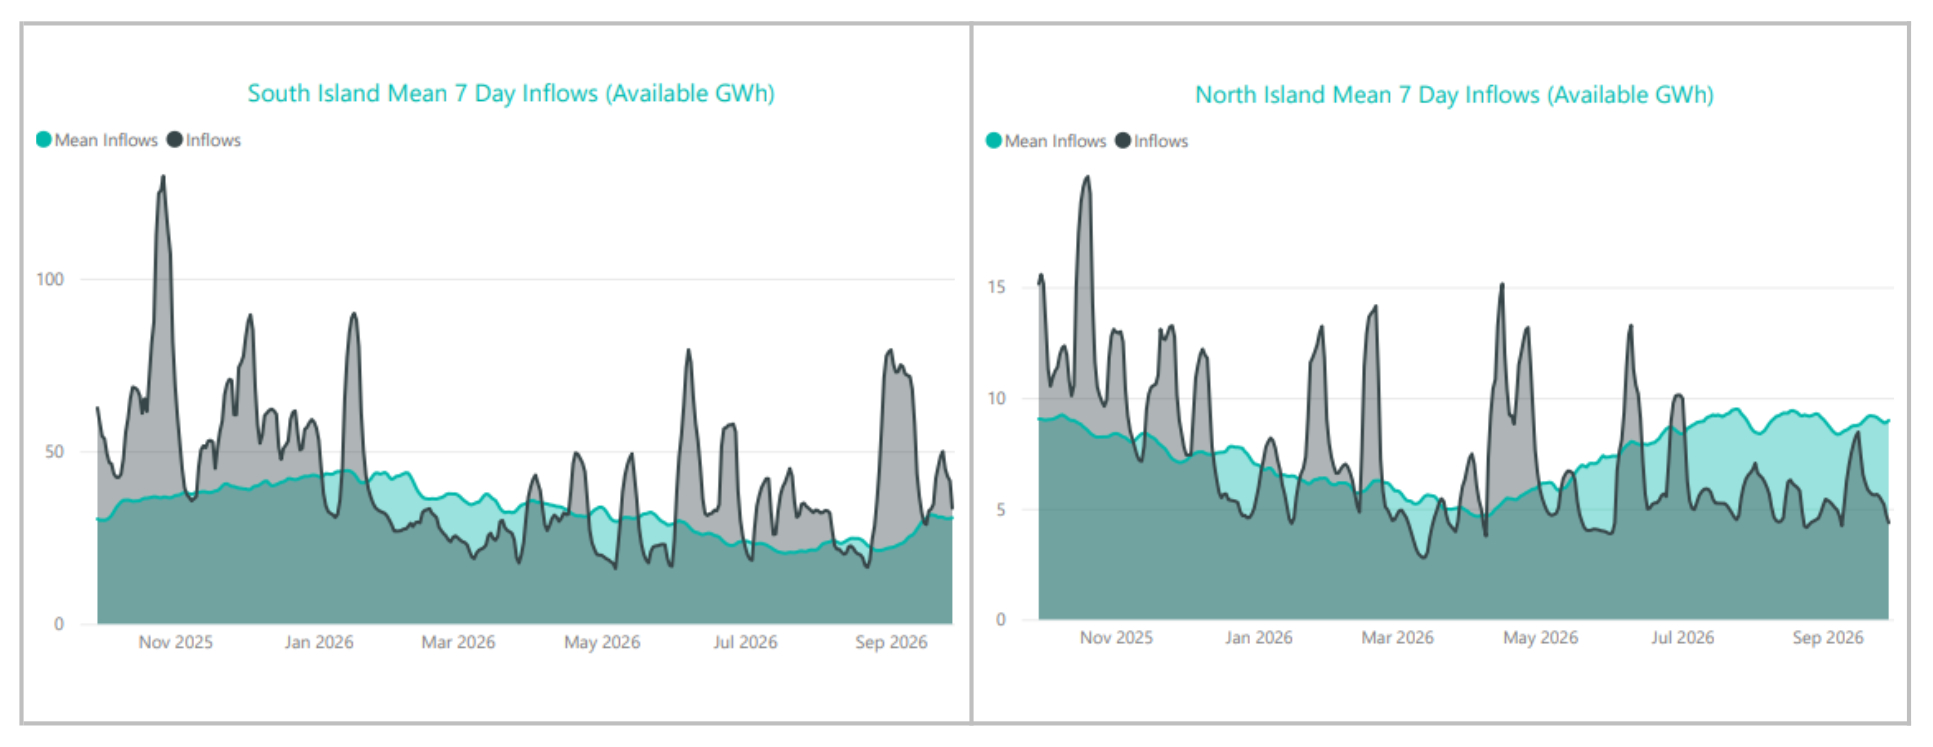
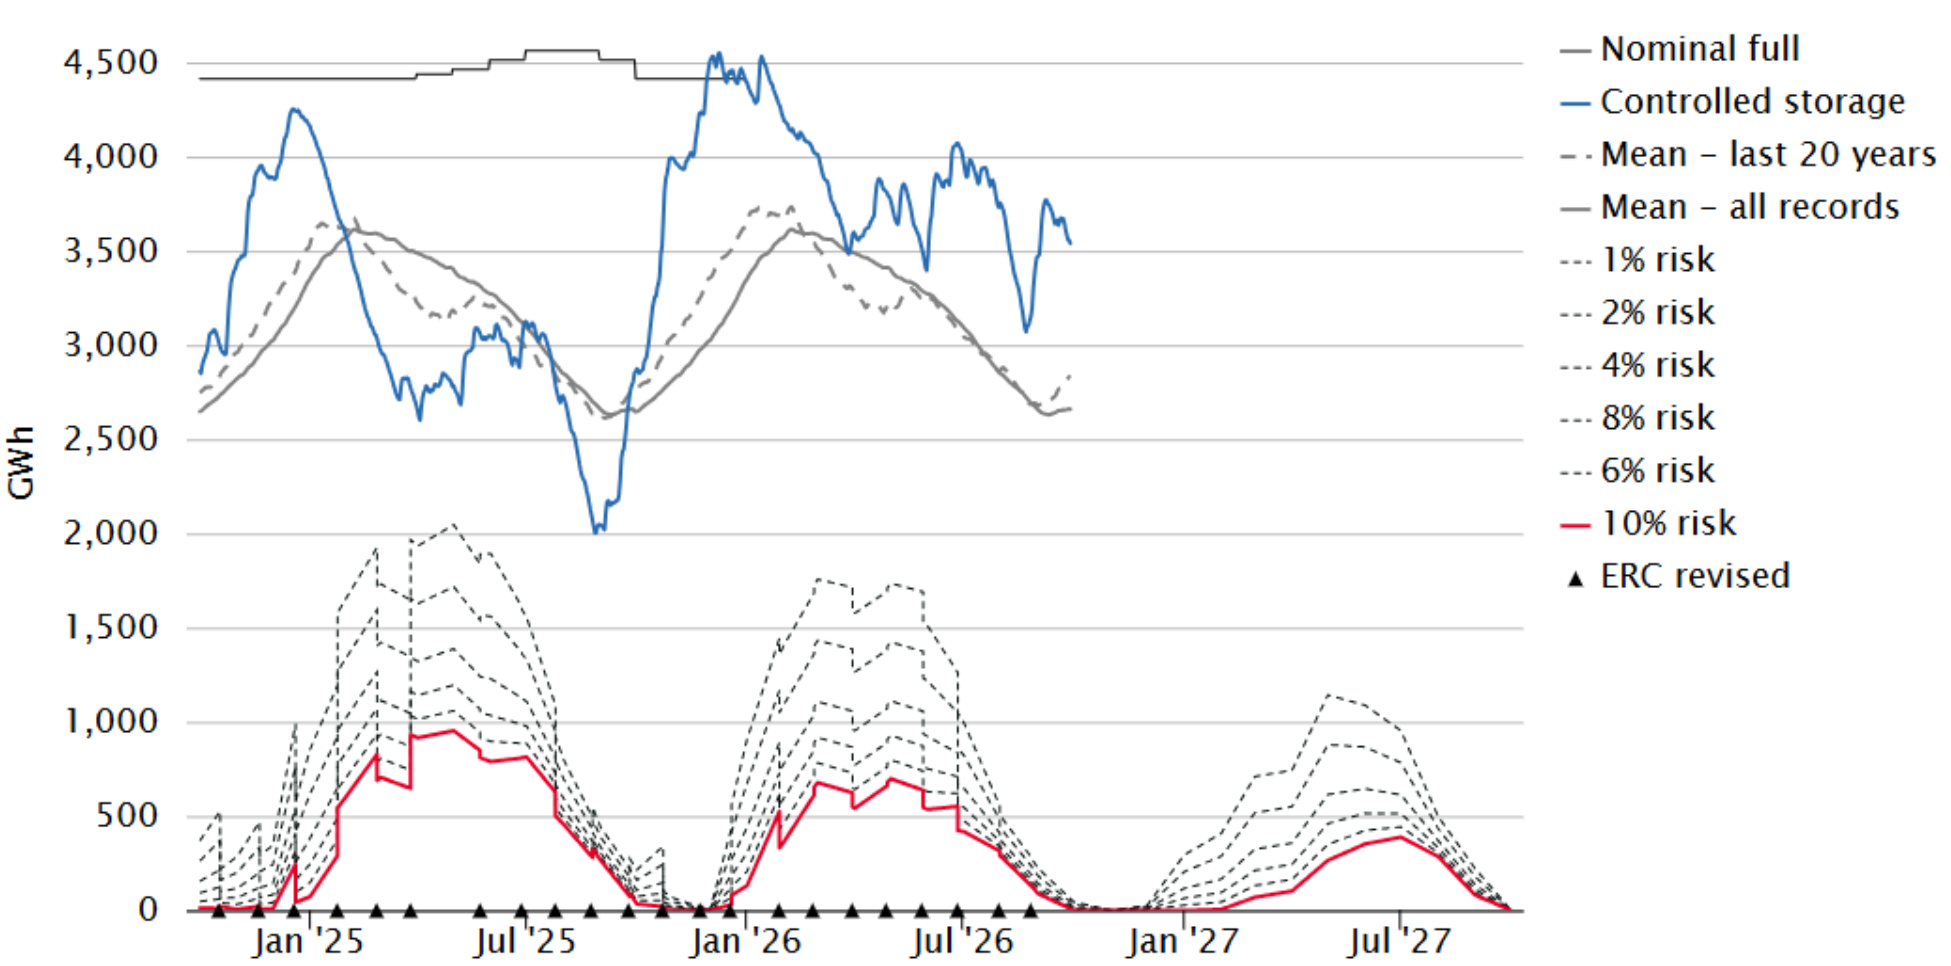
High SI inflows at the start of September resulted in storage increasing significantly before falling later in the month. Overall energy storage levels increased 89 GWh during the month to end at 3,540GWh (80% full). Storage remains well above the average level for this time of year. The following chart shows the latest breakdown of storage across the main hydro catchments.
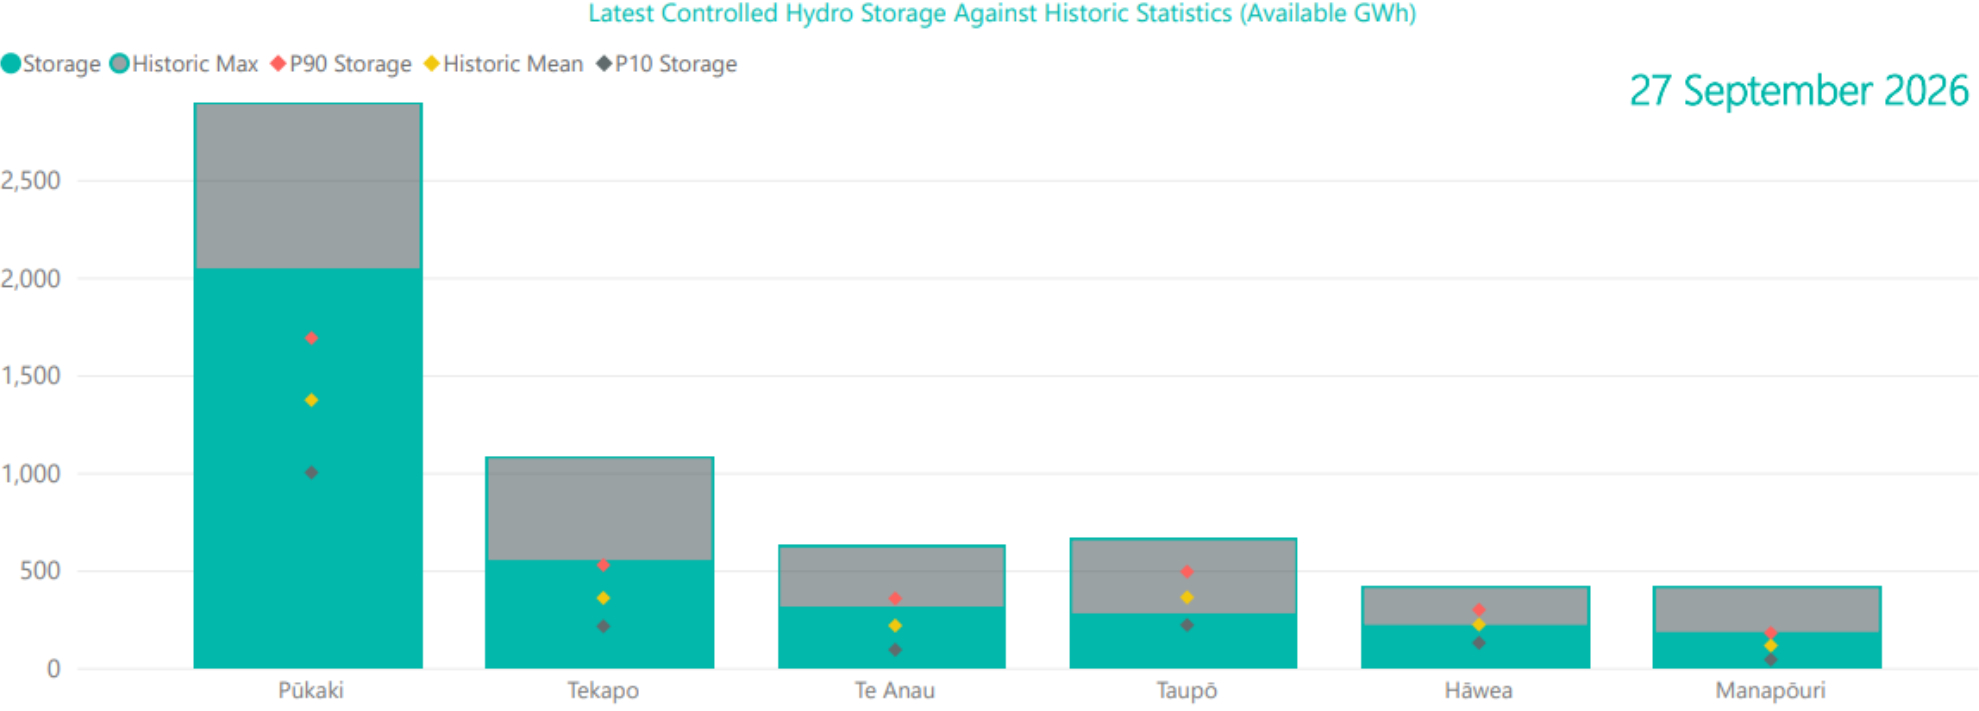
Security of supply risks remained low in September, with storage levels well above average, as shown below.
Snowpack
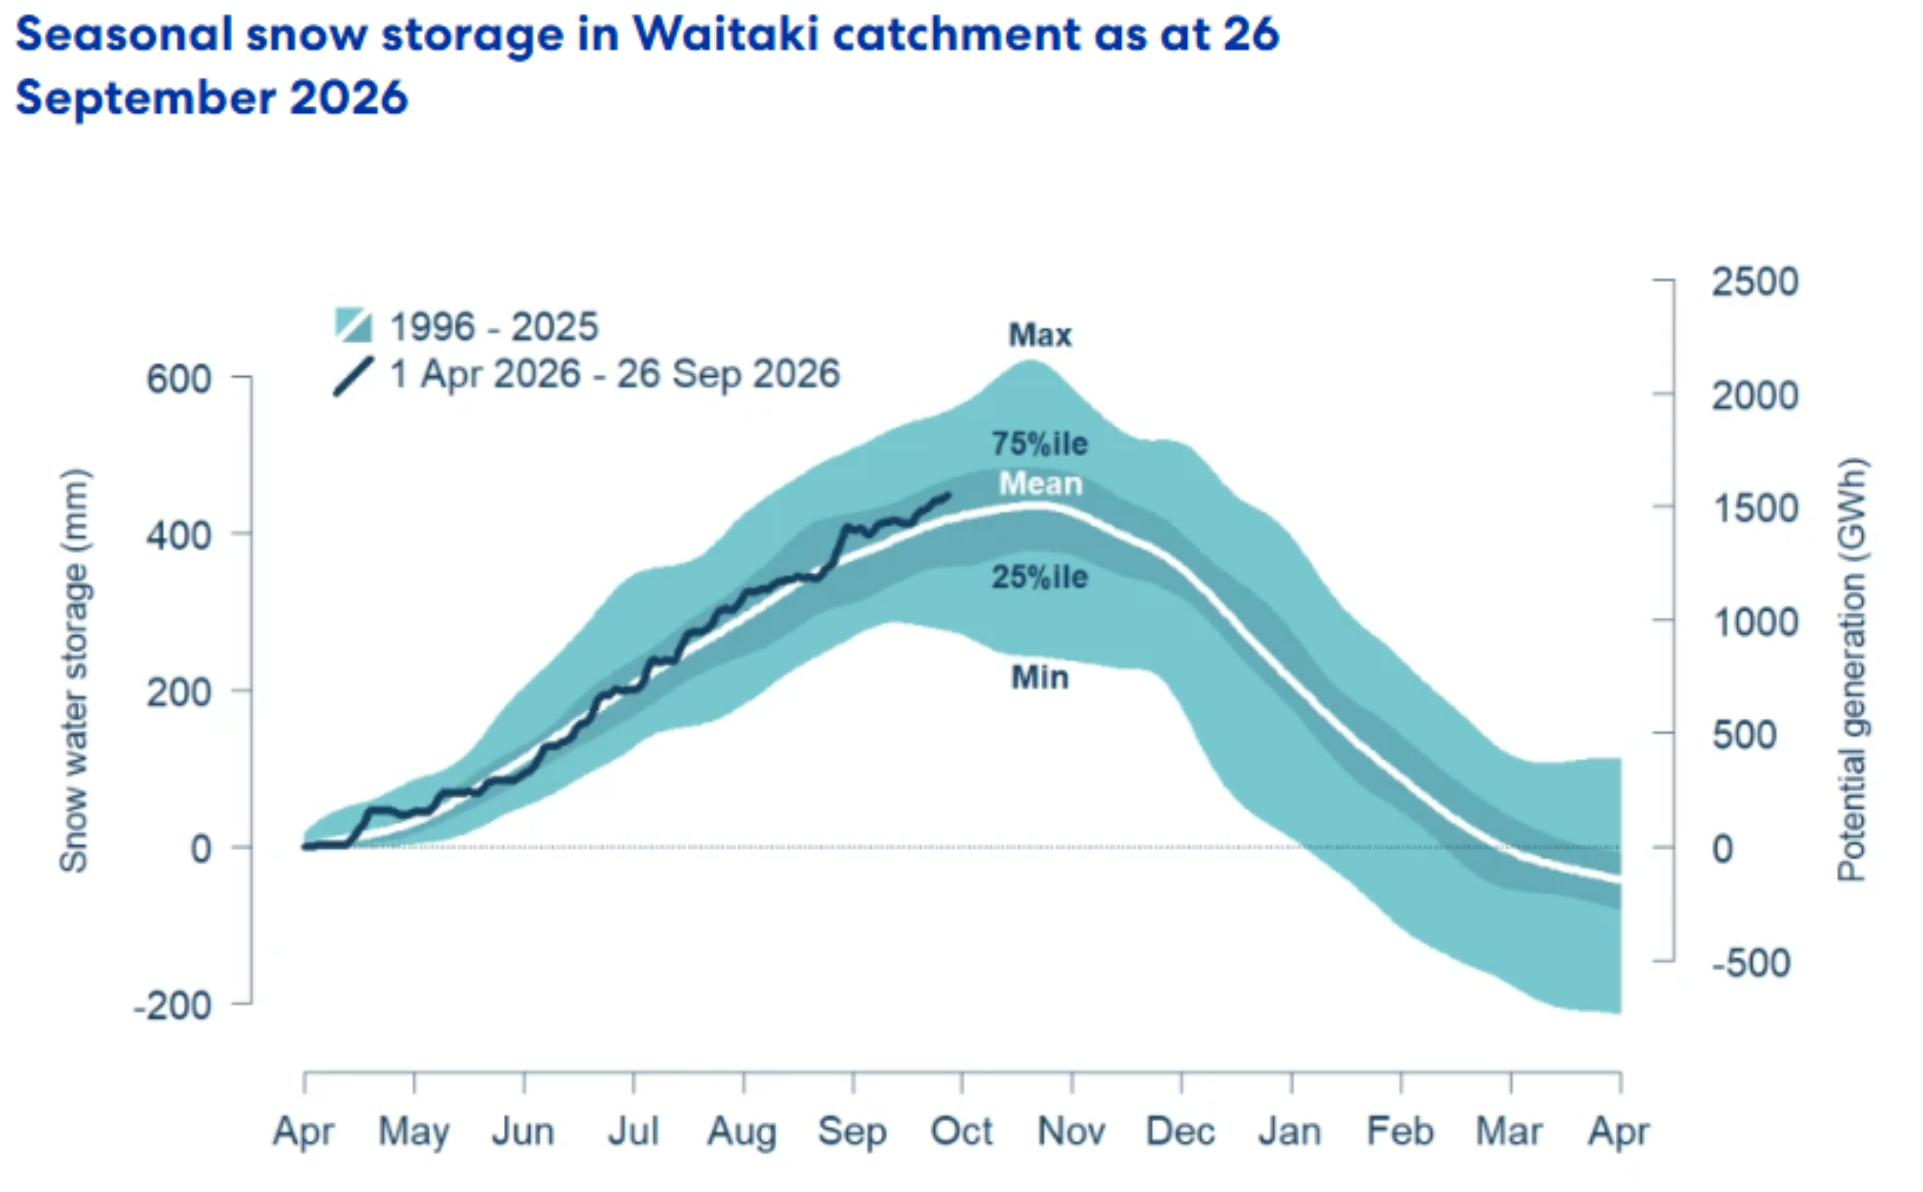
Snowpack is an important form of stored hydro energy during winter and is released as inflows during spring. The following graph shows that the snowpack in the important Waitaki catchment increased during September and is close to the 75th percentile for this time of year, based on observations from the past 30 years.
Climate outlook overview September - November 2025 (from NIWA)
- Very strong El Niño conditions are now present in the tropical Pacific and are expected to strengthen further. El Niño’s influence on New Zealand’s weather patterns is becoming increasingly apparent and is expected to be a dominant driver of climate patterns during the outlook period.
- El Niño is expected to favour more frequent westerly airflows over New Zealand, along with increased wind strength and gustiness. This pattern is likely to bring more frequent fronts to western and southern areas, while increasing the potential for dry, warm föhn conditions in eastern regions.
- At times, this pattern may be disrupted by stratospheric influences favouring a positive Southern Annular Mode (SAM), which can partly counteract the circulation patterns associated with El Niño.
- Additionally, it’s important to remember that El Niño does not prevent short-lived departures from the typical El Niño pattern, including occasional northerly flows that may result in heavy rainfall for parts of the country.
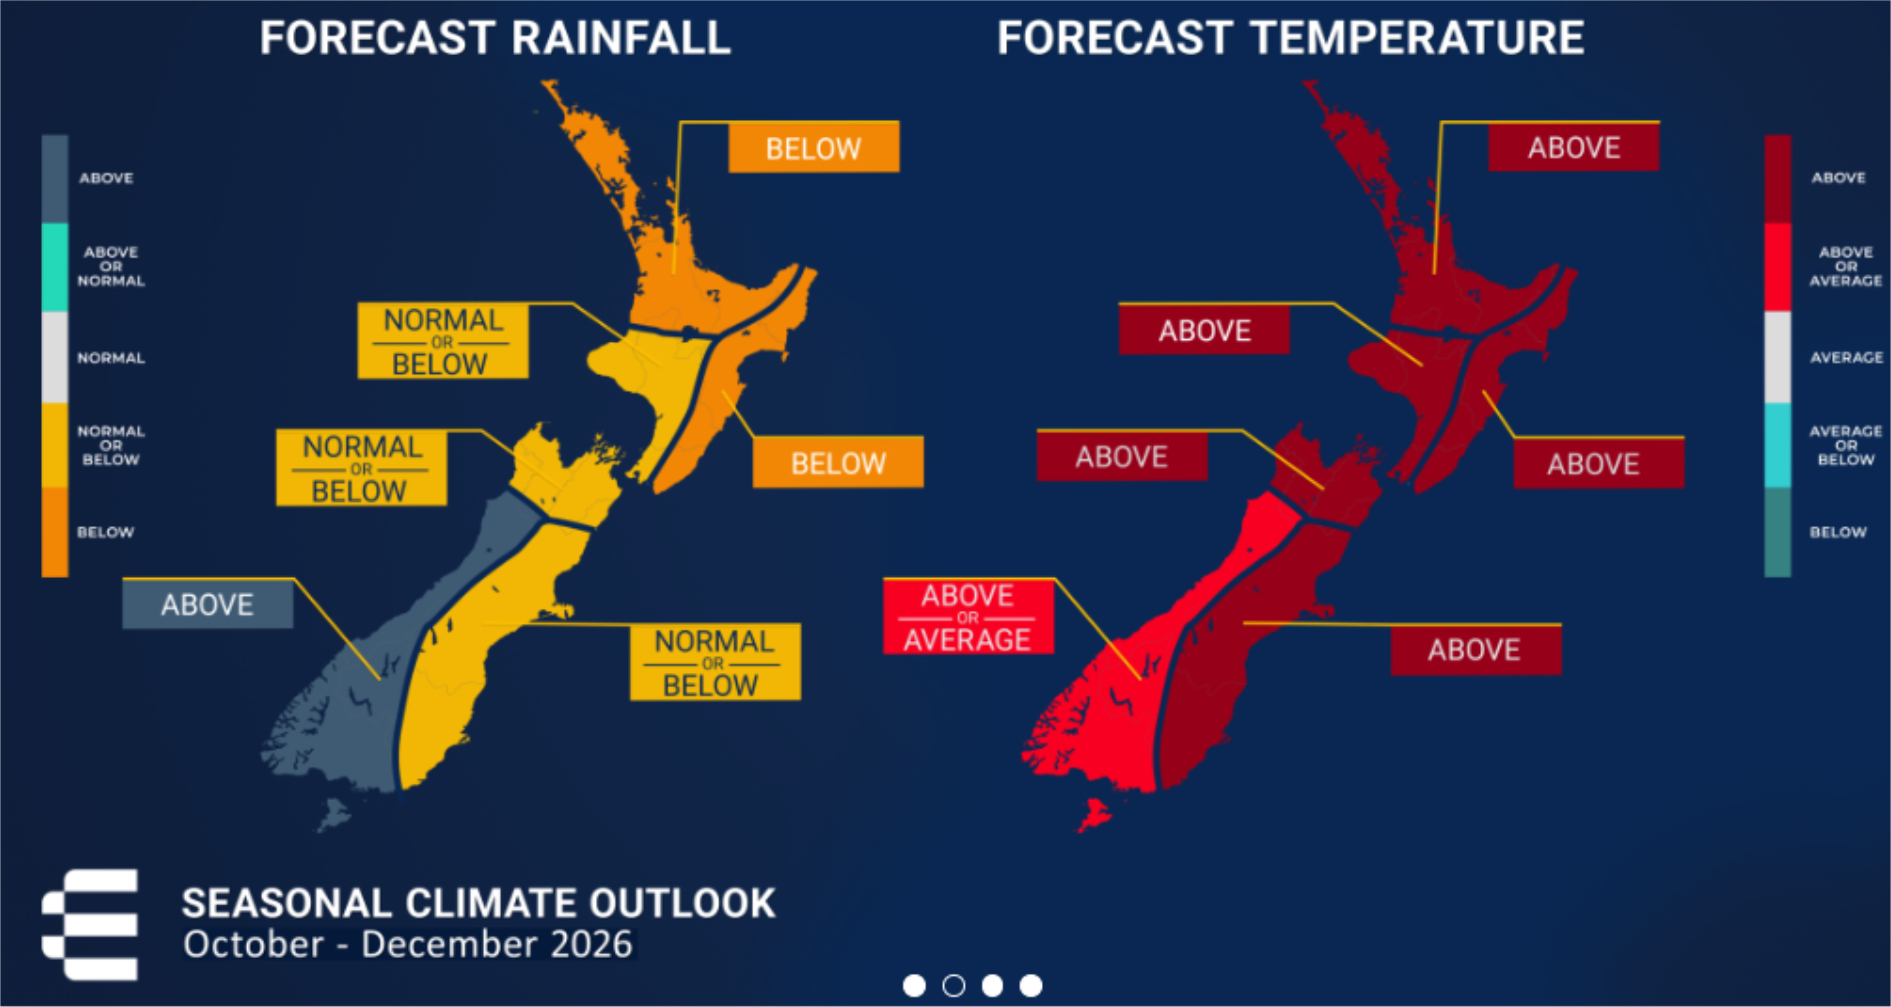
- Temperatures for October–December 2026 are most likely to be above average across most of New Zealand. In the west of the South Island, near average or above average temperatures are about equally likely. Despite the overall warmer outlook, temperatures are expected to be more variable than usual, with pronounced swings between warm and cold conditions.
- Rainfall totals for October–December 2026 are most likely to be below normal in the north and east of the North Island, while above normal rainfall is most likely in the west of the South Island. Elsewhere, near normal or below normal rainfall are about equally likely over the outlook period as a whole.
- Soil moisture, river flows, and snow and lake storage are currently generally healthy across the South Island, while below normal soil moisture and river flows are evident in parts of the North Island. The north and east of the North Island are particularly likely to experience reduced rainfall, more frequent dry spells, and increased drying of soils and vegetation, potentially creating challenges for water-reliant sectors.
- Soil moisture levels and river flows are most likely to be near normal or below normal across most of New Zealand, while near normal conditions are favoured in the west of the South Island.
- El Niño is expected to peak in late spring or early summer, with the potential for significant impacts. The event is likely to rank among the strongest on record, as anticipated over recent months (see El Niño 2026: What you need to know). The Relative Oceanic Niño Index (RONI) has already exceeded 1997 values for this time of year and has undergone the most rapid warming on record.
- Out-of-season Southwest Pacific tropical cyclones (July–October) are rare and, when they do occur, are more common during El Niño conditions. This remote risk does not currently factor into New Zealand’s Seasonal Climate Outlook, although active monitoring remains in place. The tropical cyclone season formally begins on 1 November.
The Wholesale Gas Market
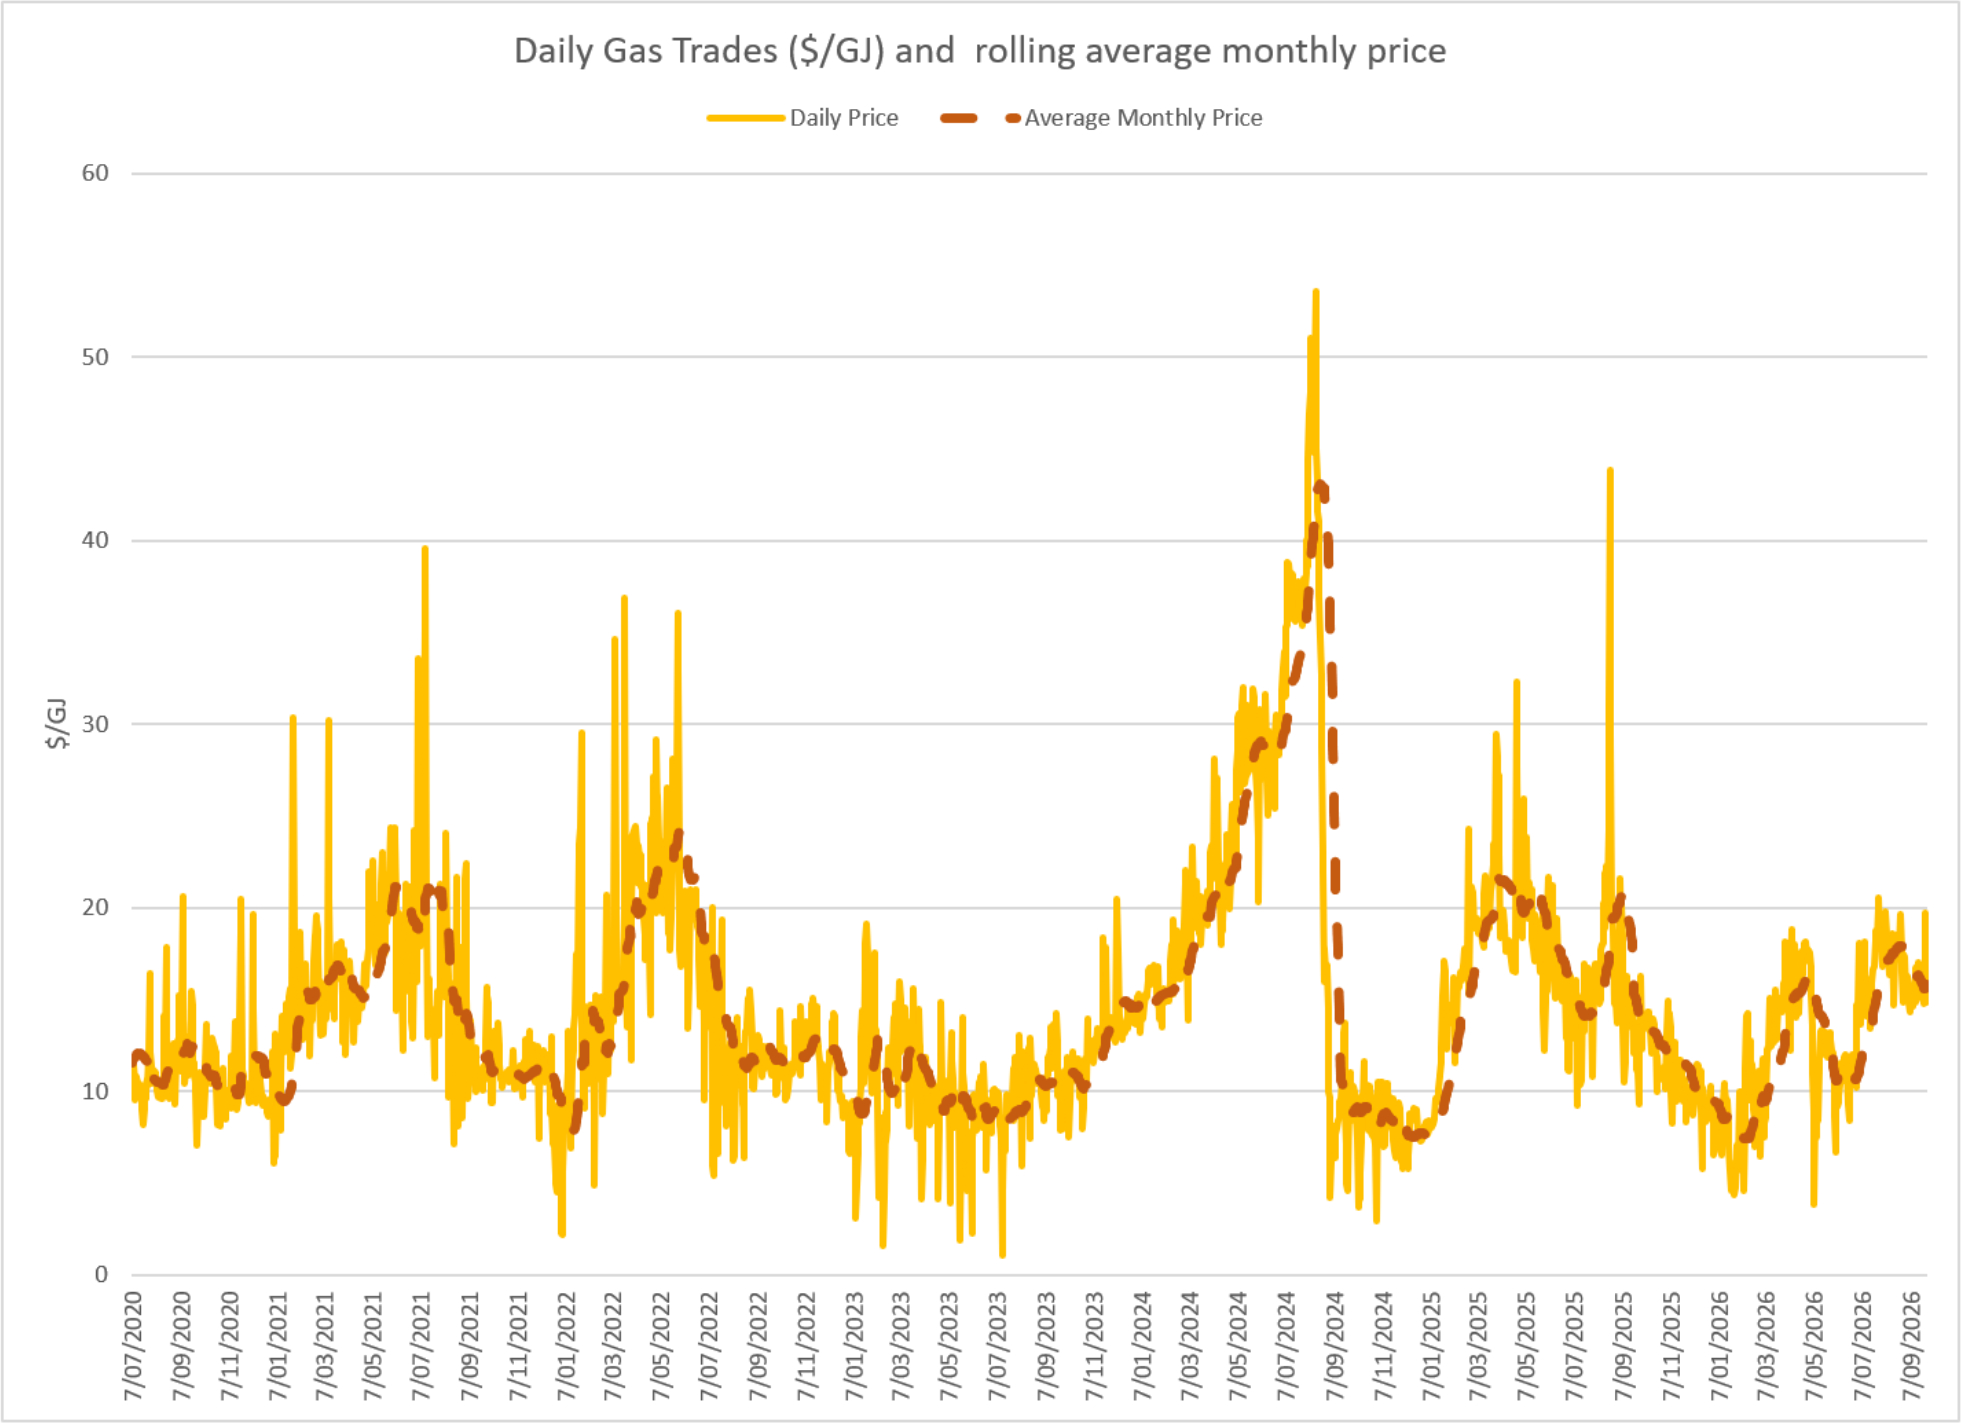
Spot gas prices decreased through September. Prices for the month averaged $15.8/GJ – a 9% decrease compared to August. Average prices are 9% above what they were at the same time last year. Spot gas prices include the cost of carbon, which is currently around $2/GJ.
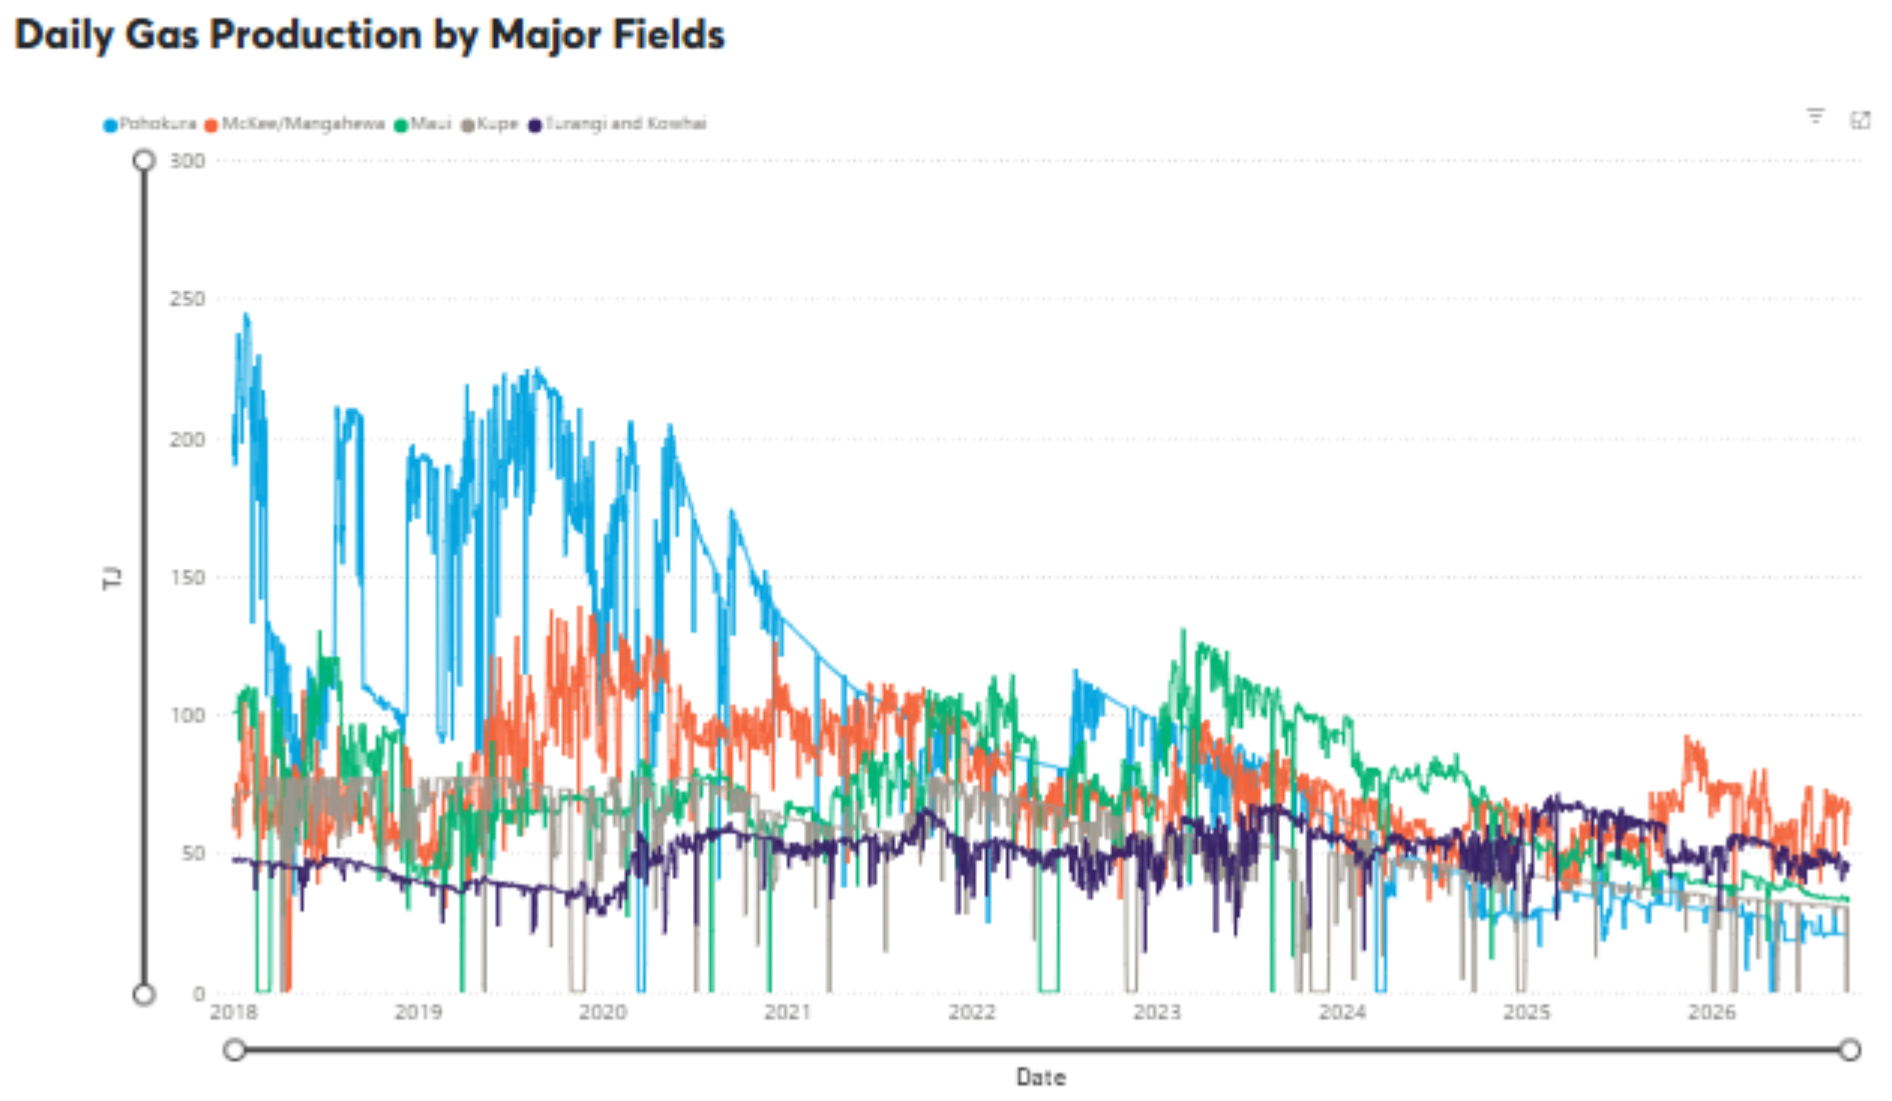
On the supply side, most fields maintained output throughout September. McKee/Mangahewa was the exception, with production increasing to an average of just over 65 TJ/day. Turangi and Kowhai fell slightly, averaging 46TJ/day. Pohokura maintained production at 21 TJ/day, while Maui averaged 34 TJ/day. Kupe experienced a short outage but maintained output of 30.5 TJ/day before and after the outage.
The following graph shows production levels from major fields over the last 7 years.
On the demand side, Huntly reduced its gas consumption during the month, averaging 12.4 TJ/day. Methanex maintained usage at close to 70TJ/day through September. Ballance started the month using close to 20 TJ/day, reducing to about 15TJ/day in the middle of the month and staying at that level.
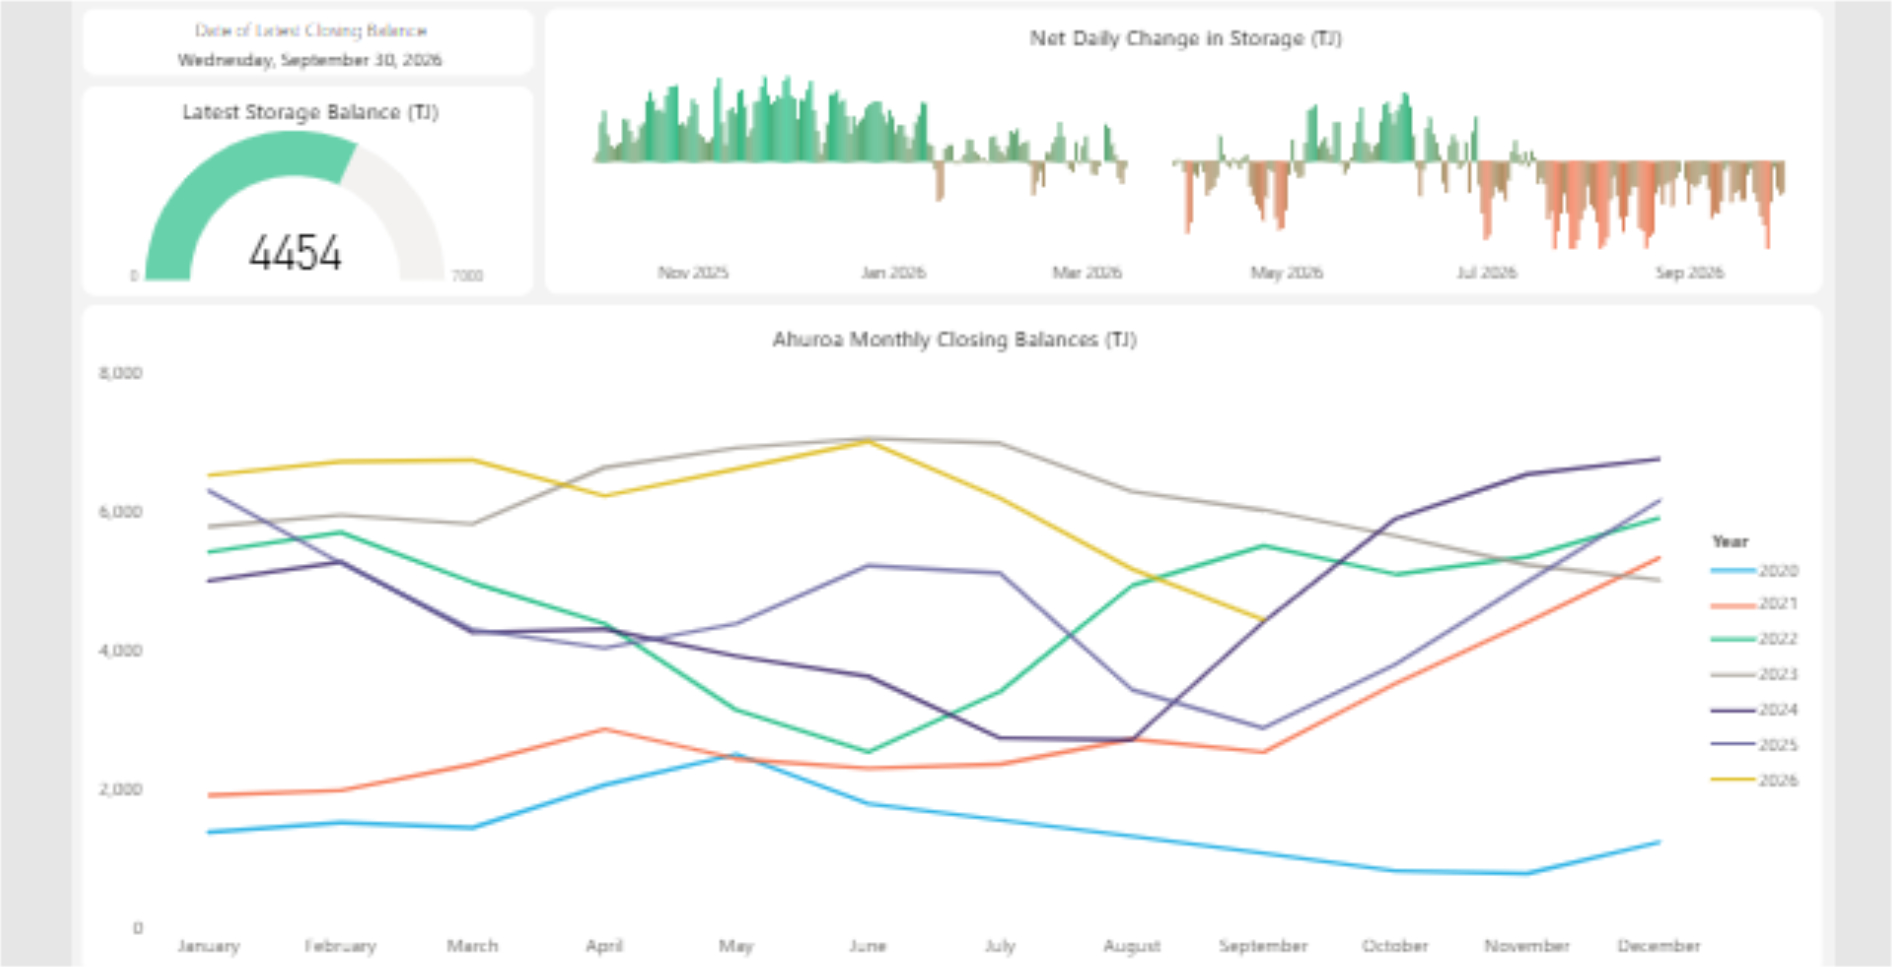
Gas storage is becoming increasingly important as falling production coincides with more variable demand, particularly from gas-fired electricity generation. The following chart shows how storage at Ahuroa decreased again in September but remains above average levels seen at this time of year over the last few years.
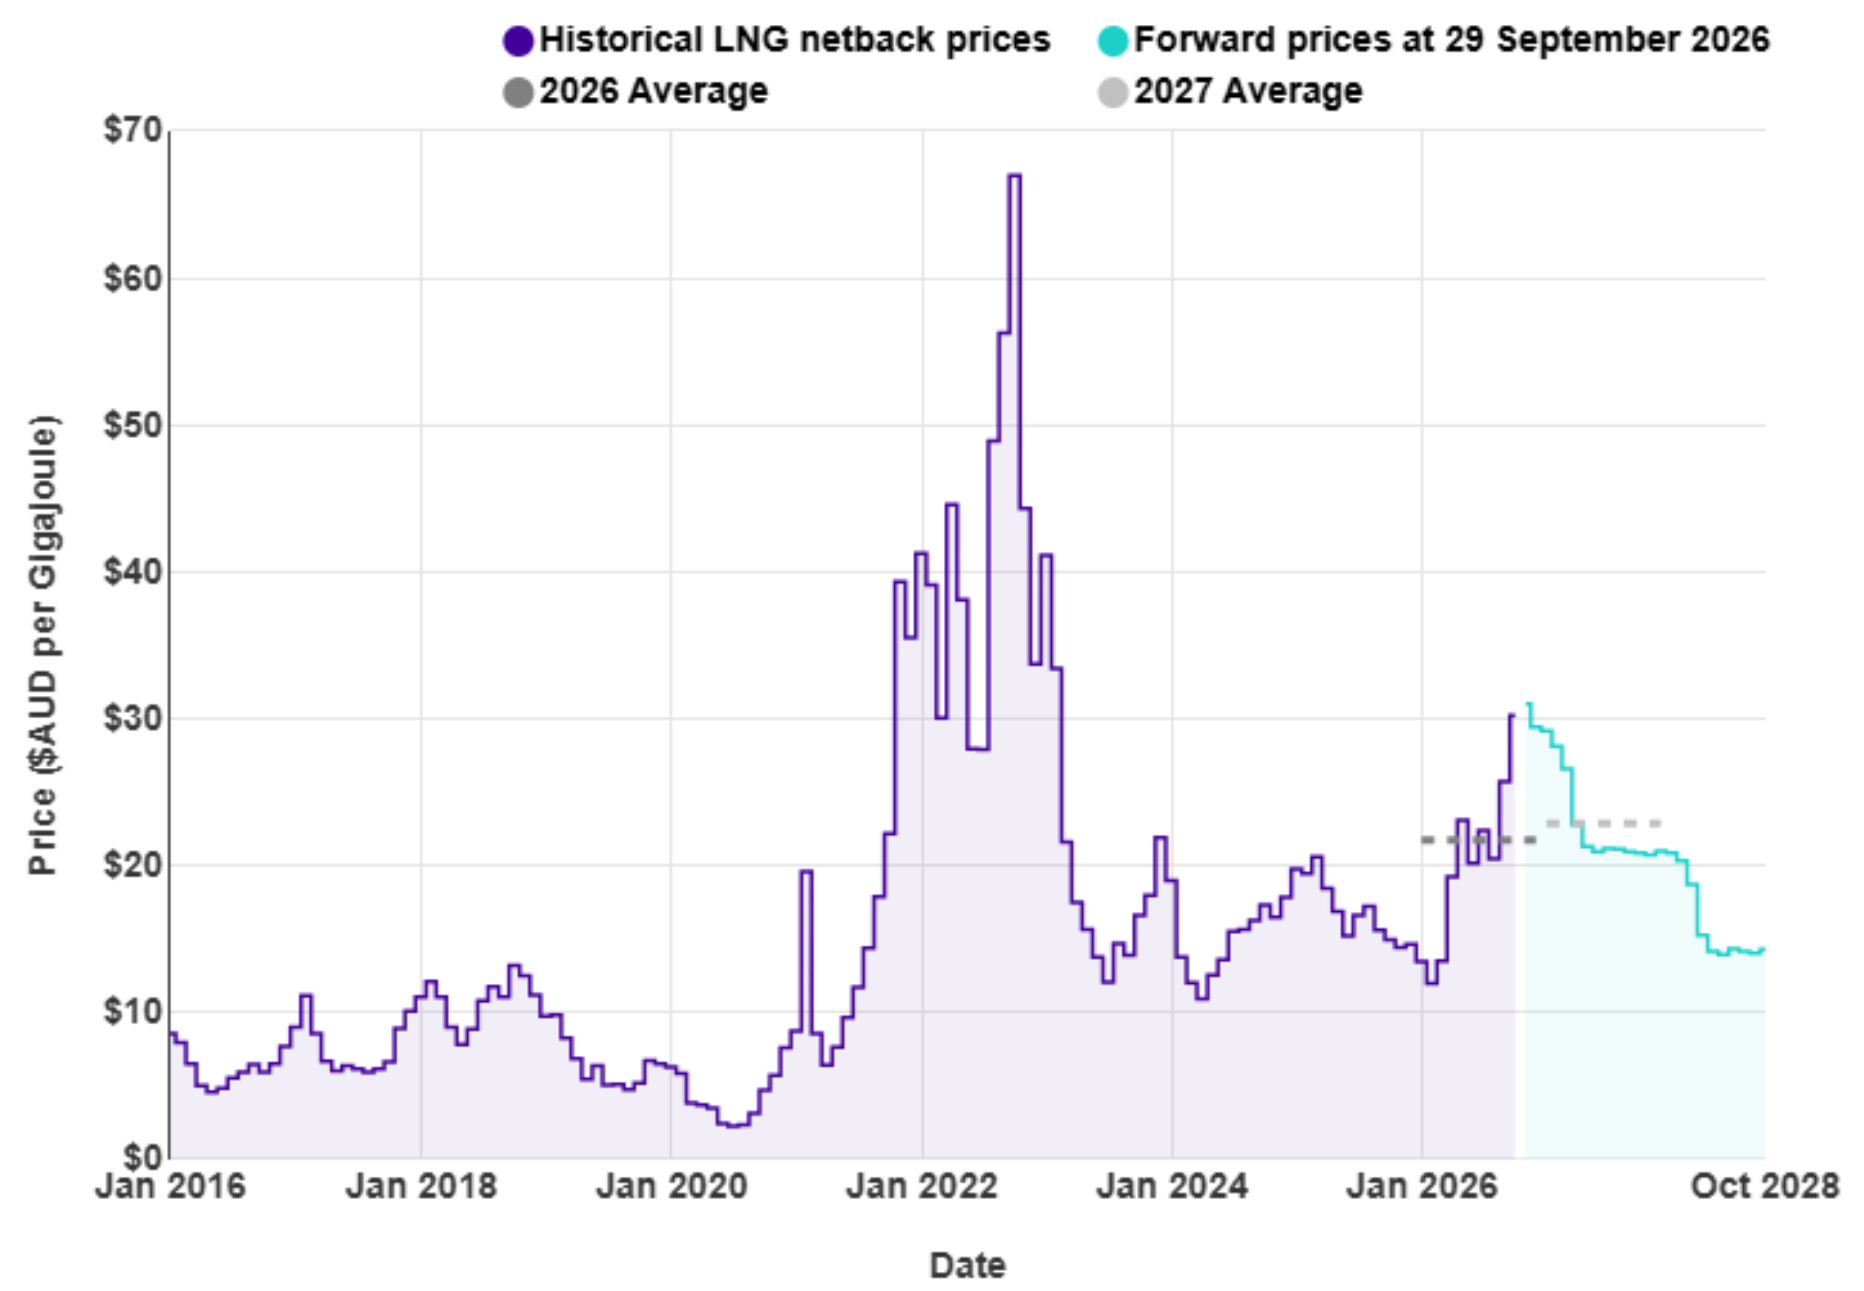
International LNG netback prices have increased because of the conflict in the Middle East. Prices in September increased another 17% to $30.24/GJ. Forecast average prices are currently $21.70/GJ for 2026 and $22.90/GJ for 2027. (Note that netback prices are indicative of international prices – they are produced by the ACCC and quoted in Australian dollars. They are net of the estimated costs to convert from pipeline gas in Australia to LNG, hence the term “netback”)
New Zealand does not yet have an LNG import or export market, so our domestic prices are not directly linked to global prices, though this may change with the Government announcing that an LNG import terminal will be built in the next few years.
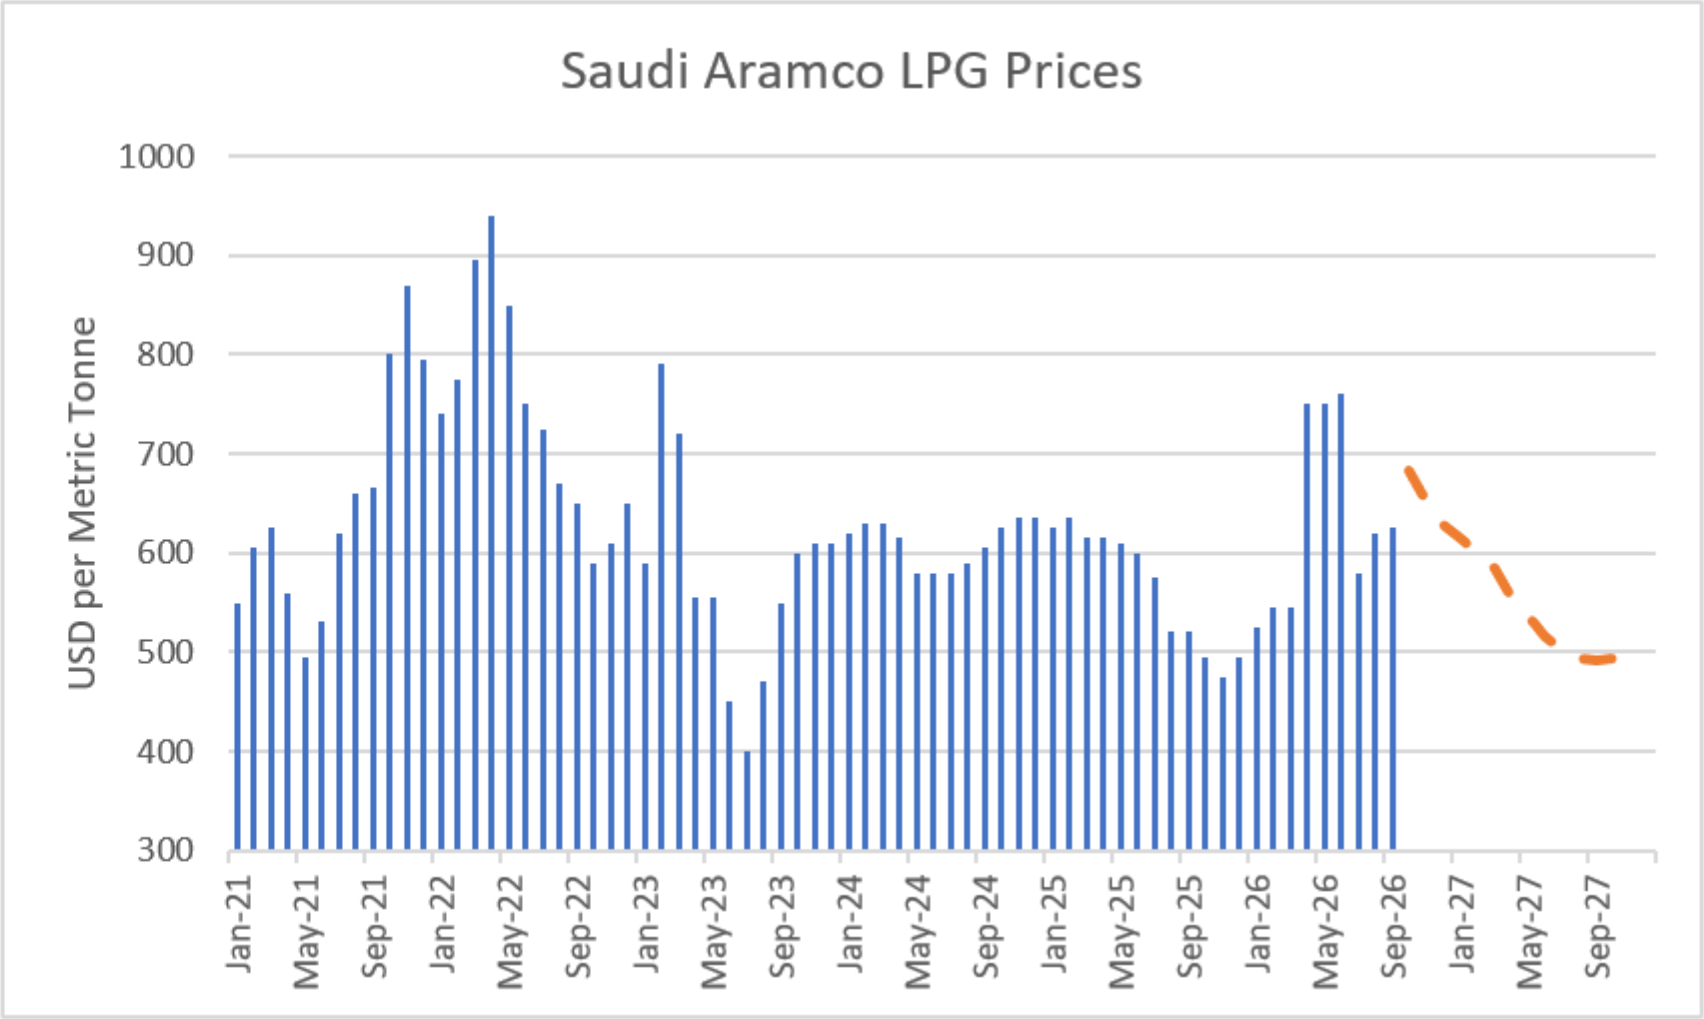
LPG is an important fuel for many large energy users, particularly in areas where reticulated natural gas is not available. The contract price of LPG is typically set by international benchmarks such as the Saudi Aramco LPG prices, which are normally quoted in US dollars per metric tonne.
The following graph shows the Saudi Aramco LPG pricing for the last 5 years as well as forecast pricing for the year and a half ahead. The conflict in the Middle East caused prices to spike from April to June but they fell steeply in July before rising again in August. Futures prices increased through September.
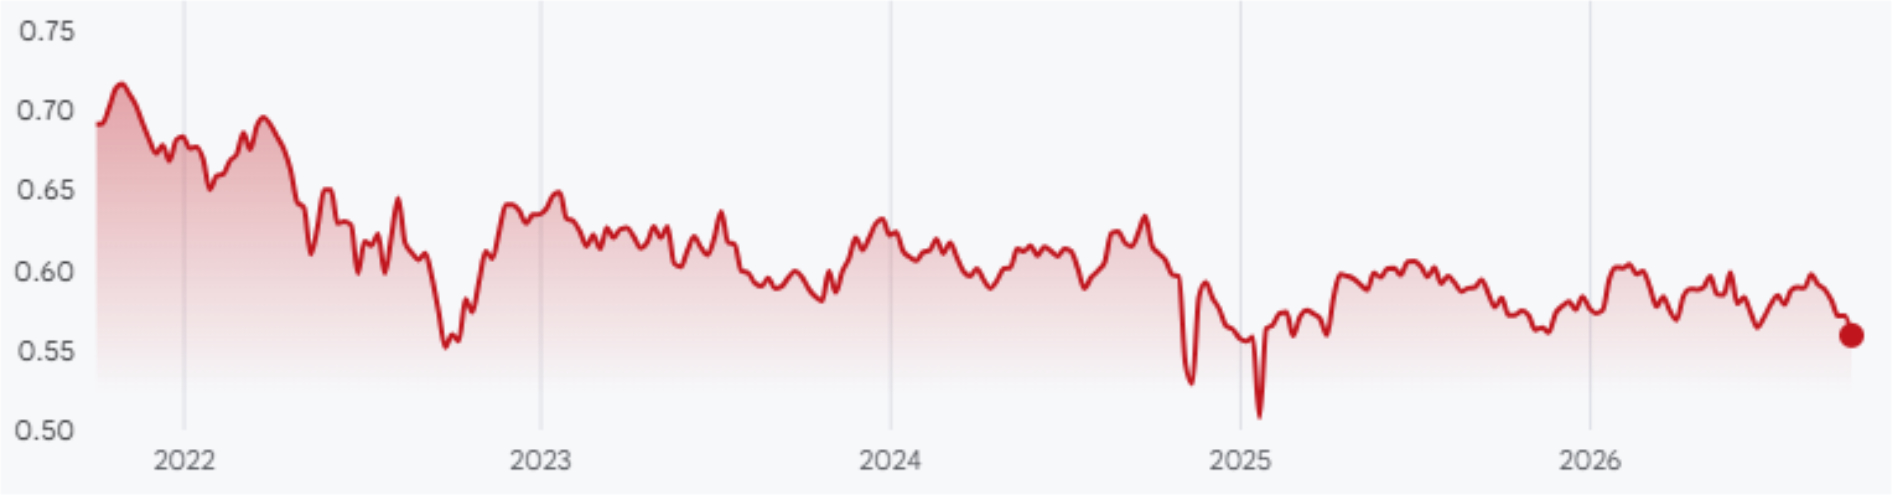
The other main contributing factor to LPG prices in New Zealand is the exchange rate against the USD. The exchange rate was around 0.59 at the start of the month and declined steadily, ending below 0.56. This remains below the average levels seen in recent years. The recent decreases would tend to push up LPG prices when quoted in NZD.
The Coal Market
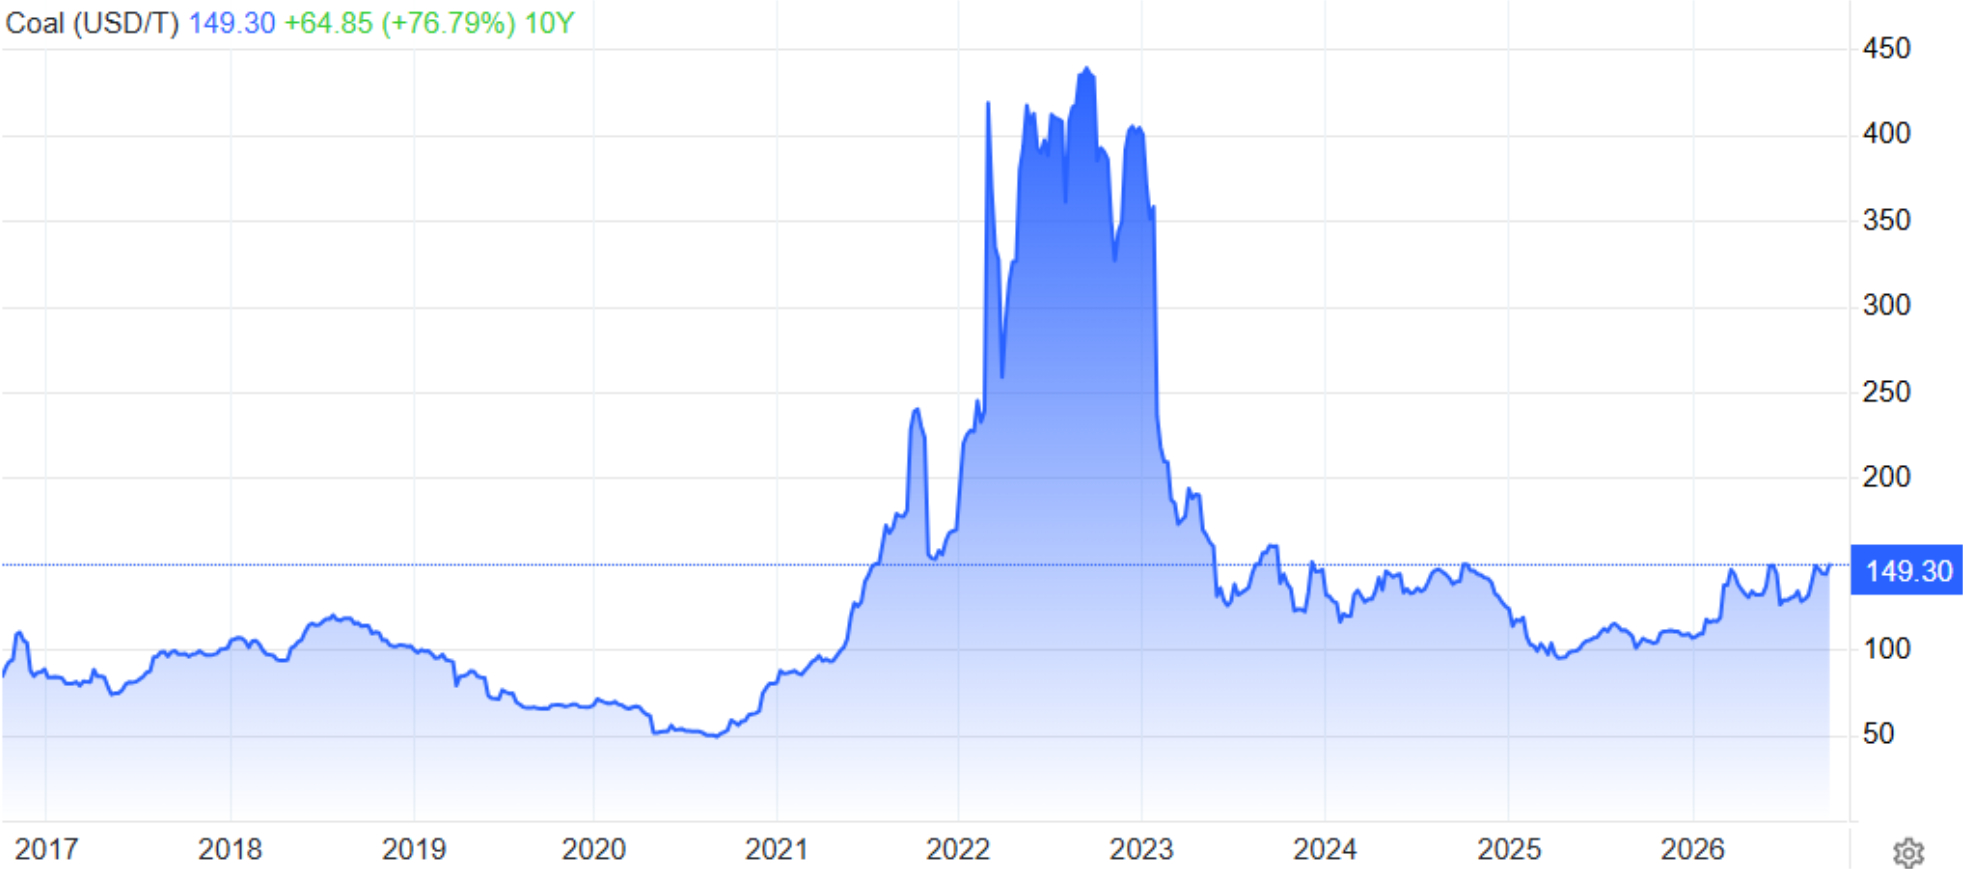
The conflict in the Middle East has contributed to an increase in coal prices along with other international energy commodities. To date the impact has not been as great as that observed during the initial years of the Ukraine war. Prices remained relatively flat for most of September but ended the month at $149/tonne, an increase of 5%. The following graph shows prices over the past 10 years.
Like gas prices, coal prices can flow through to the electricity market.
Carbon Pricing
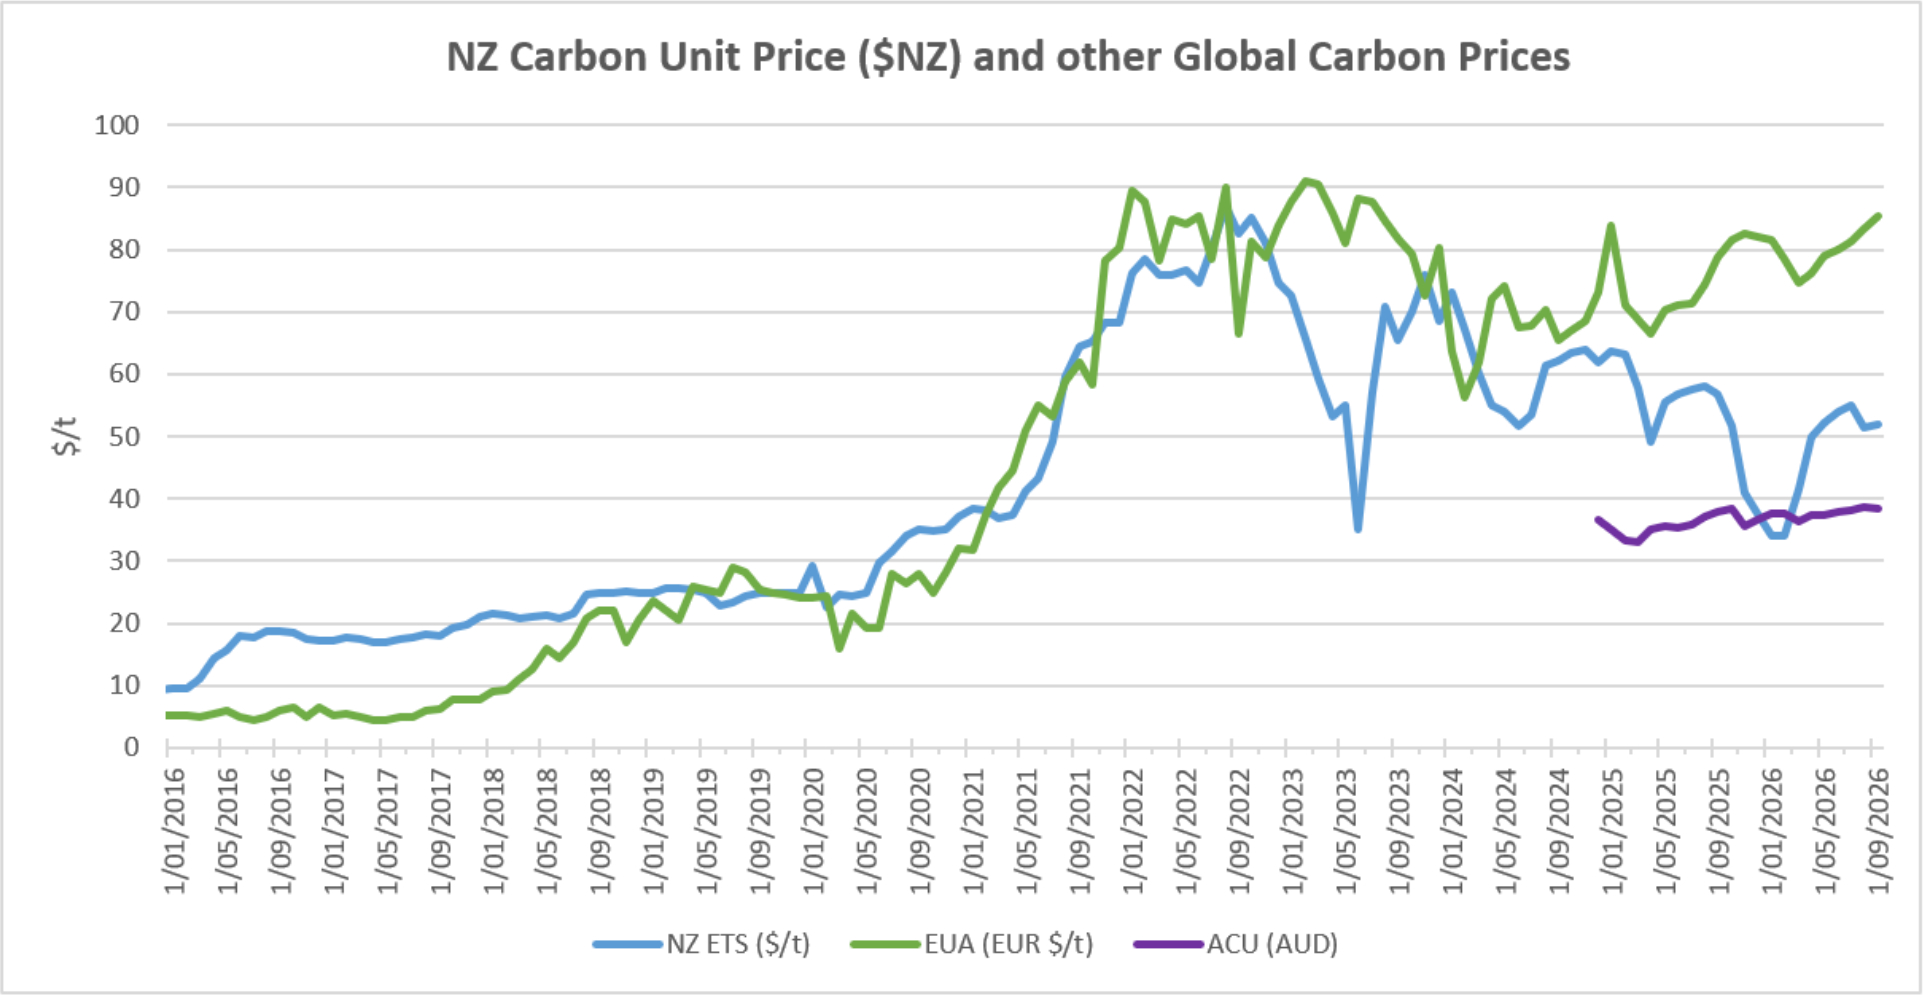
NZ has had an Emissions Trading Scheme (ETS) in place since 2008. It has subsequently been reviewed by several governments and is now an “uncapped” price scheme closely linked to international schemes. However, there are “upper and lower guardrails” set up to prevent wild swings in carbon price that act as maximum and minimum prices. These increased in December 2023 to $173 and $64, respectively. Carbon prices increased marginally in September, up 1% at $52.
As the carbon price rises, the cost of coal, gas or other fossil fuels used in process heat applications will naturally also rise. Electricity prices are also affected by a rising carbon price. Electricity prices are set by the marginal producing unit – in NZ this is currently typically coal or gas or hydro generators, with the latter valuing the cost of its water against the former. An increase in carbon price can lead to an increase in electricity prices in the short to medium term (as the marginal units set the price). A carbon price of $50/t is estimated to currently add about $25/MWh (or ~2.5c/kWh) to electricity prices. In the long term the impact should reduce as money is invested in more low-cost renewables and there is less reliance on gas and coal fired generation.
EU carbon units increased by 2% in September to €85.48 per tonne. Australian carbon units fell by 1% to A$38.35.
About this Report:
This energy market summary report provides information on wholesale price trends within the NZ Electricity Market. Please note that all electricity prices are presented as a $ per MWh price and all carbon prices as a $ per unit price. All spot prices are published by the Electricity Authority. Futures contract prices are sourced from ASX.
Further information can be found at the locations noted below.
- Transpower publishes a range of detailed information, which can be found here: https://www.transpower.co.nz/power-system-live-data
- The Electricity Authority publishes a range of detailed information, which can be found here: https://www.emi.ea.govt.nz/
- Weather and Climate data – The MetService publishes a range of weather-related information, which can be found here: https://www.metservice.com/
Disclaimer: This document has been prepared for informational and explanatory purposes only and is not intended to be relied upon by any person. This document does not form part of any existing or future contract or agreement between us. We make no representation, assurance, or guarantee as to the accuracy of the information provided. To the maximum extent permitted by law, none of Smart Power Ltd, its related companies, directors, employees or agents accepts any liability for any loss arising from the use of this document or its contents or otherwise arising out of or in connection with it. You must not provide this document or any information contained in it to any third party without our prior consent.
About Smart Power:
Smart Power is a full-service Energy Management consultancy. Apart from Energy Procurement, Smart Power can also provide:
- Technical advice on how to reduce your energy use & emissions
- Sustainability Reporting
- Invoice Management Services
We also offer boutique energy and water billing services for landlords/property developers.
Contact us here or call one of our offices to talk to our experienced staff about how we can assist you with achieving your energy goals.
© Copyright, 2026. Smart Power Ltd


