

The Wholesale Electricity Market
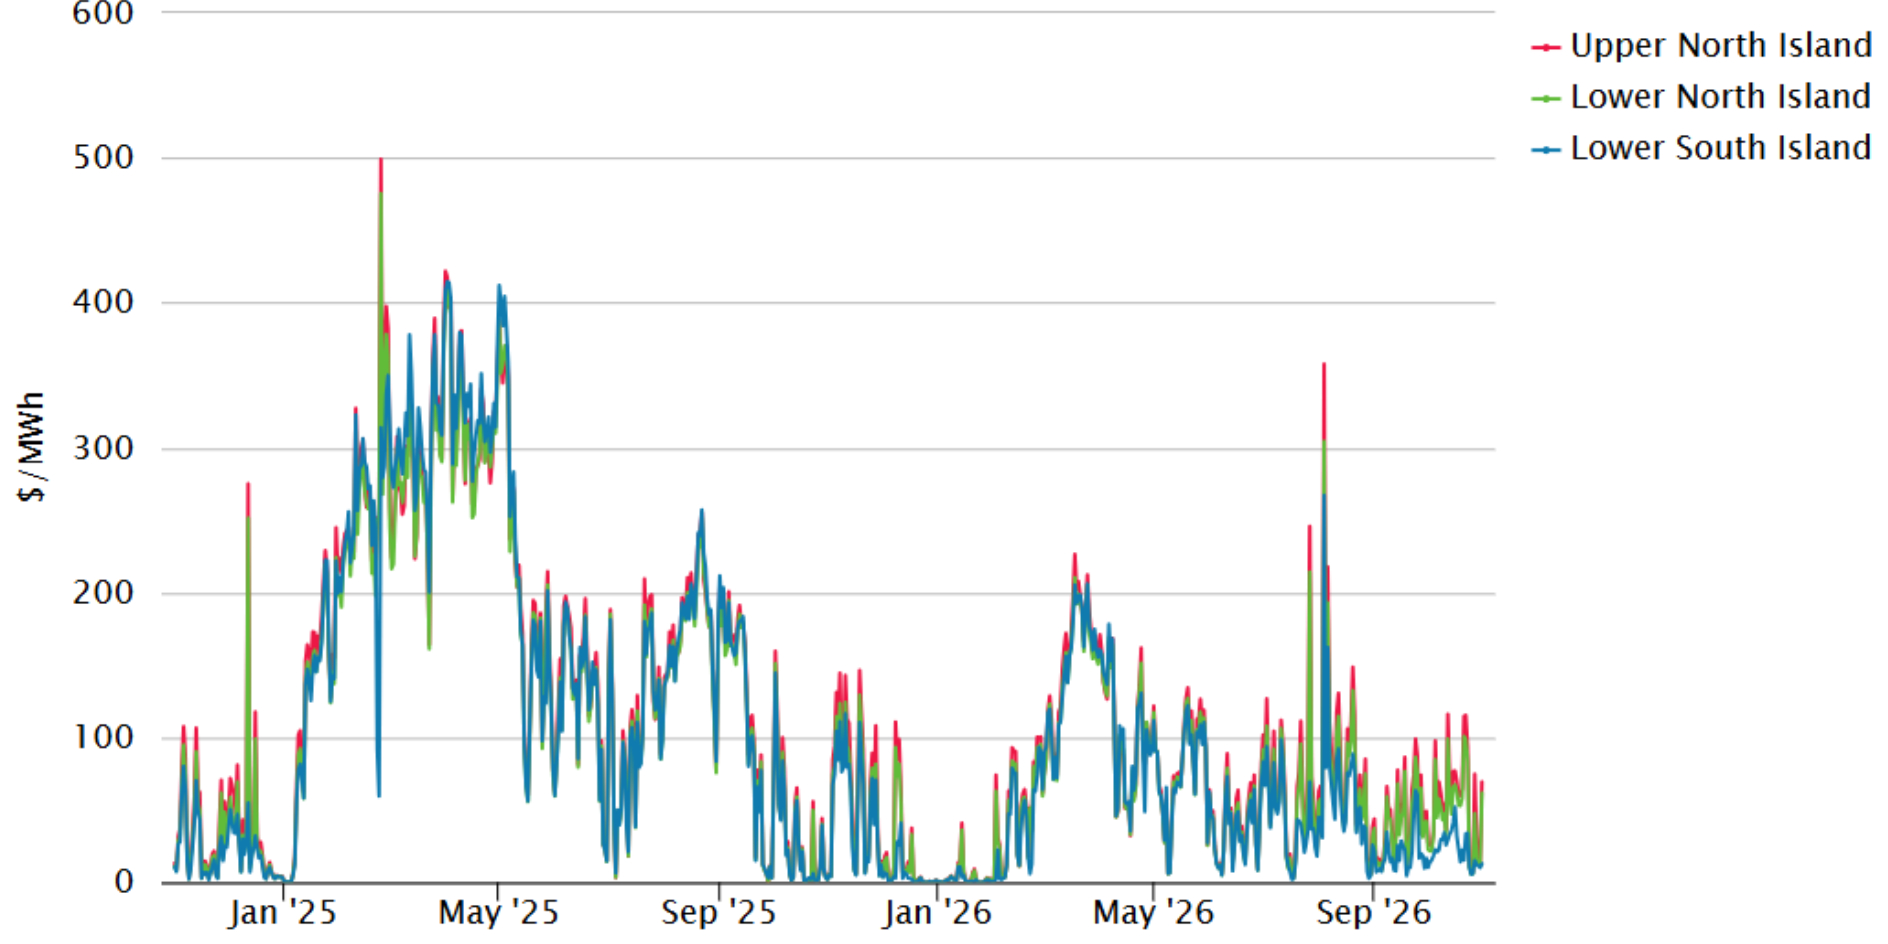
Spot prices in the wholesale electricity market remained low in October. Average spot prices for the month ranged from $22.5 in the lower South Island (up from $20 in September), to $56 in the upper North Island ($44 in September).

The following chart shows average weekly spot prices over the last two years. Recent low prices can be clearly seen to the right along with the separation of prices between the NI and SI nodes.
Electricity Demand
Demand continued to taper off as New Zealand moved through the milder spring months, however it remained at the upper end of the range observed over the past few years, as shown in the following chart.

Electricity Generation Mix
Hydro generation continued to back off as demand fell and wind and solar generation increased. Thermal generation remained low.

HVDC Transfer
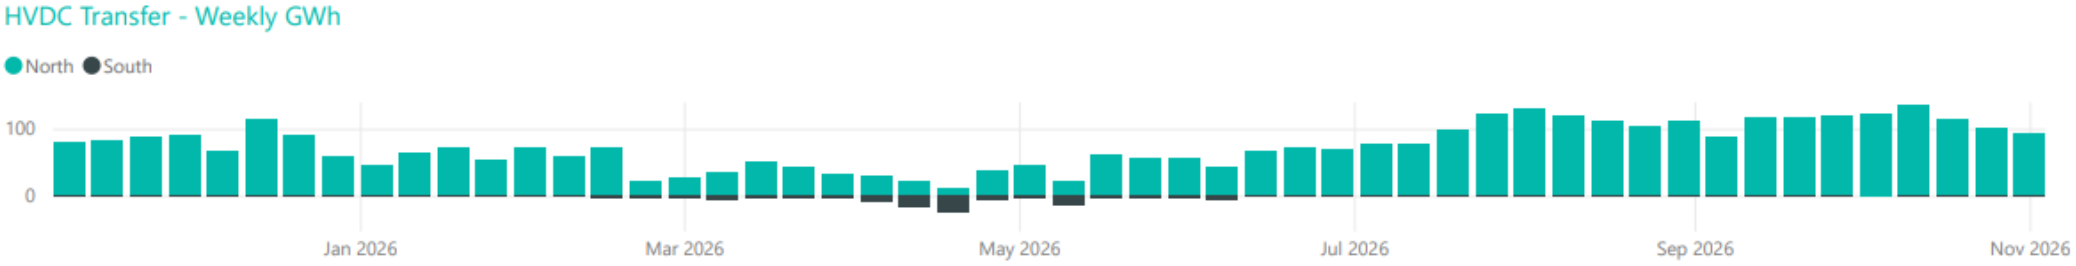
Power transfers over the HVDC link connecting the North and South Islands provide an indication of both the islands’ relative hydro positions and their reliance on thermal generation to meet demand. High northward flows tend to indicate a strong South Island hydro position, whereas southward flows indicate greater reliance on thermal generation.
Northward transfers decreased in line with the overall reduction in hydro generation. There were minimal southward transfers throughout the month.
The Electricity Futures Market
The futures market provides an indication of where market participants expect spot prices to move. Futures prices are based on actual trades between participants looking to hedge their positions (as both buyers and sellers) into the future against potential spot market volatility. Futures prices also provide a useful indication of the likely direction of retail contract prices.
The following graph shows futures prices for calendar years 2025 to 2029 at Otahuhu (Auckland) for the last 5 years.

Note that $200/MWh equates to 20c/kWh.
Forward prices decreased for 2027 but increased for the later calendar years during October. The 2027 contract fell by 6%, ending the month at $110/MWh. The 2028 contract increased by 3% to $131/MWh, while the 2029 contract rose by 3.6% to $132.50/MWh. The 2030 contract was published for the first time during October and ended the month at $139/MWh.
Known new generation projects are shown below, with additions, removals and changes highlighted in bold.

Hydro Storage
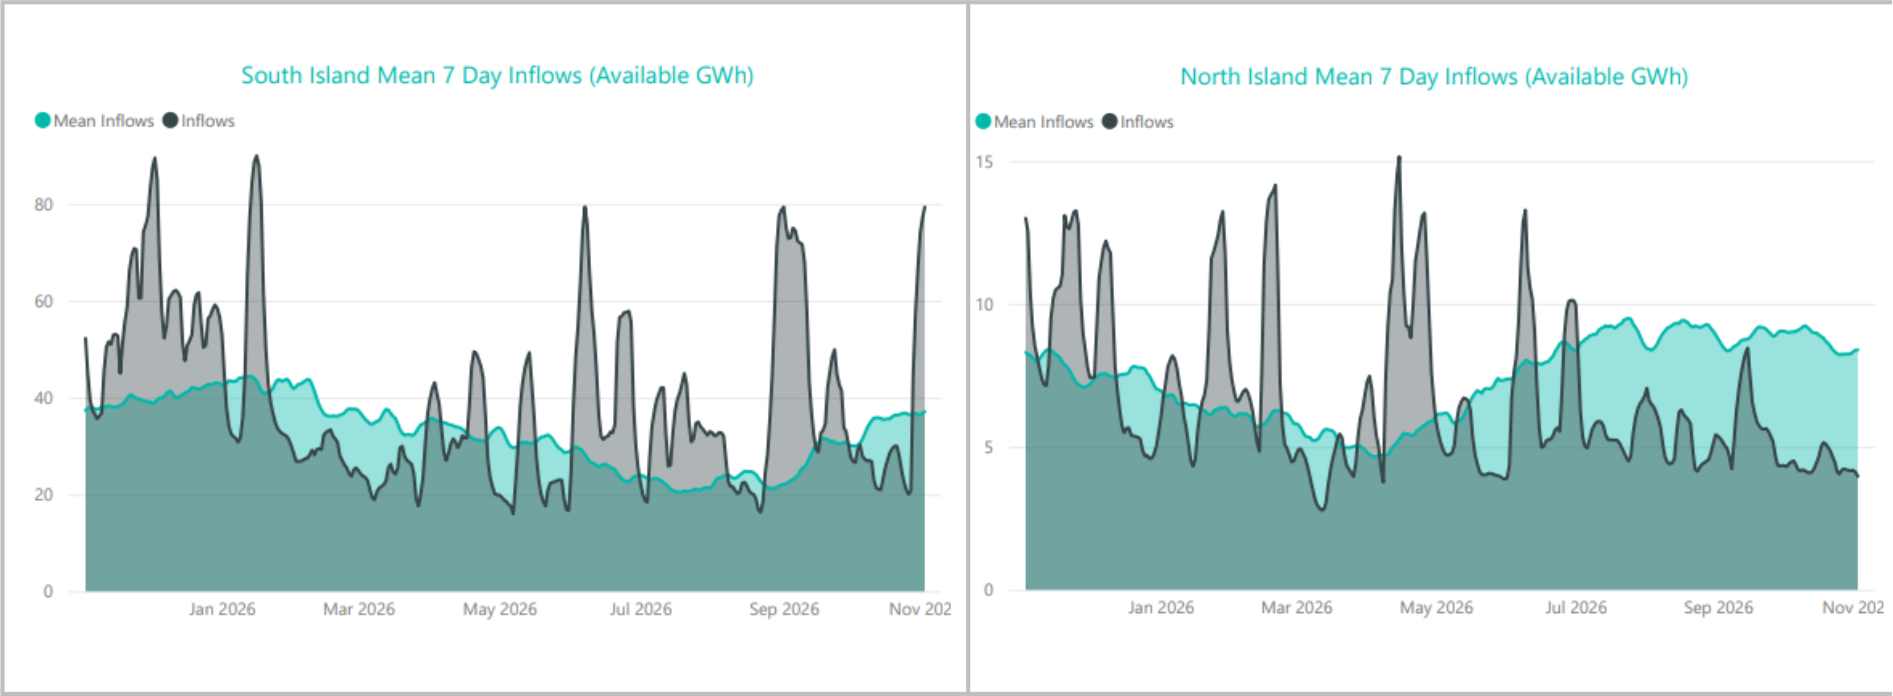
South Island inflows were below average throughout most of October but increased significantly at the end of the month. North Island inflows remained well below average, as shown below.
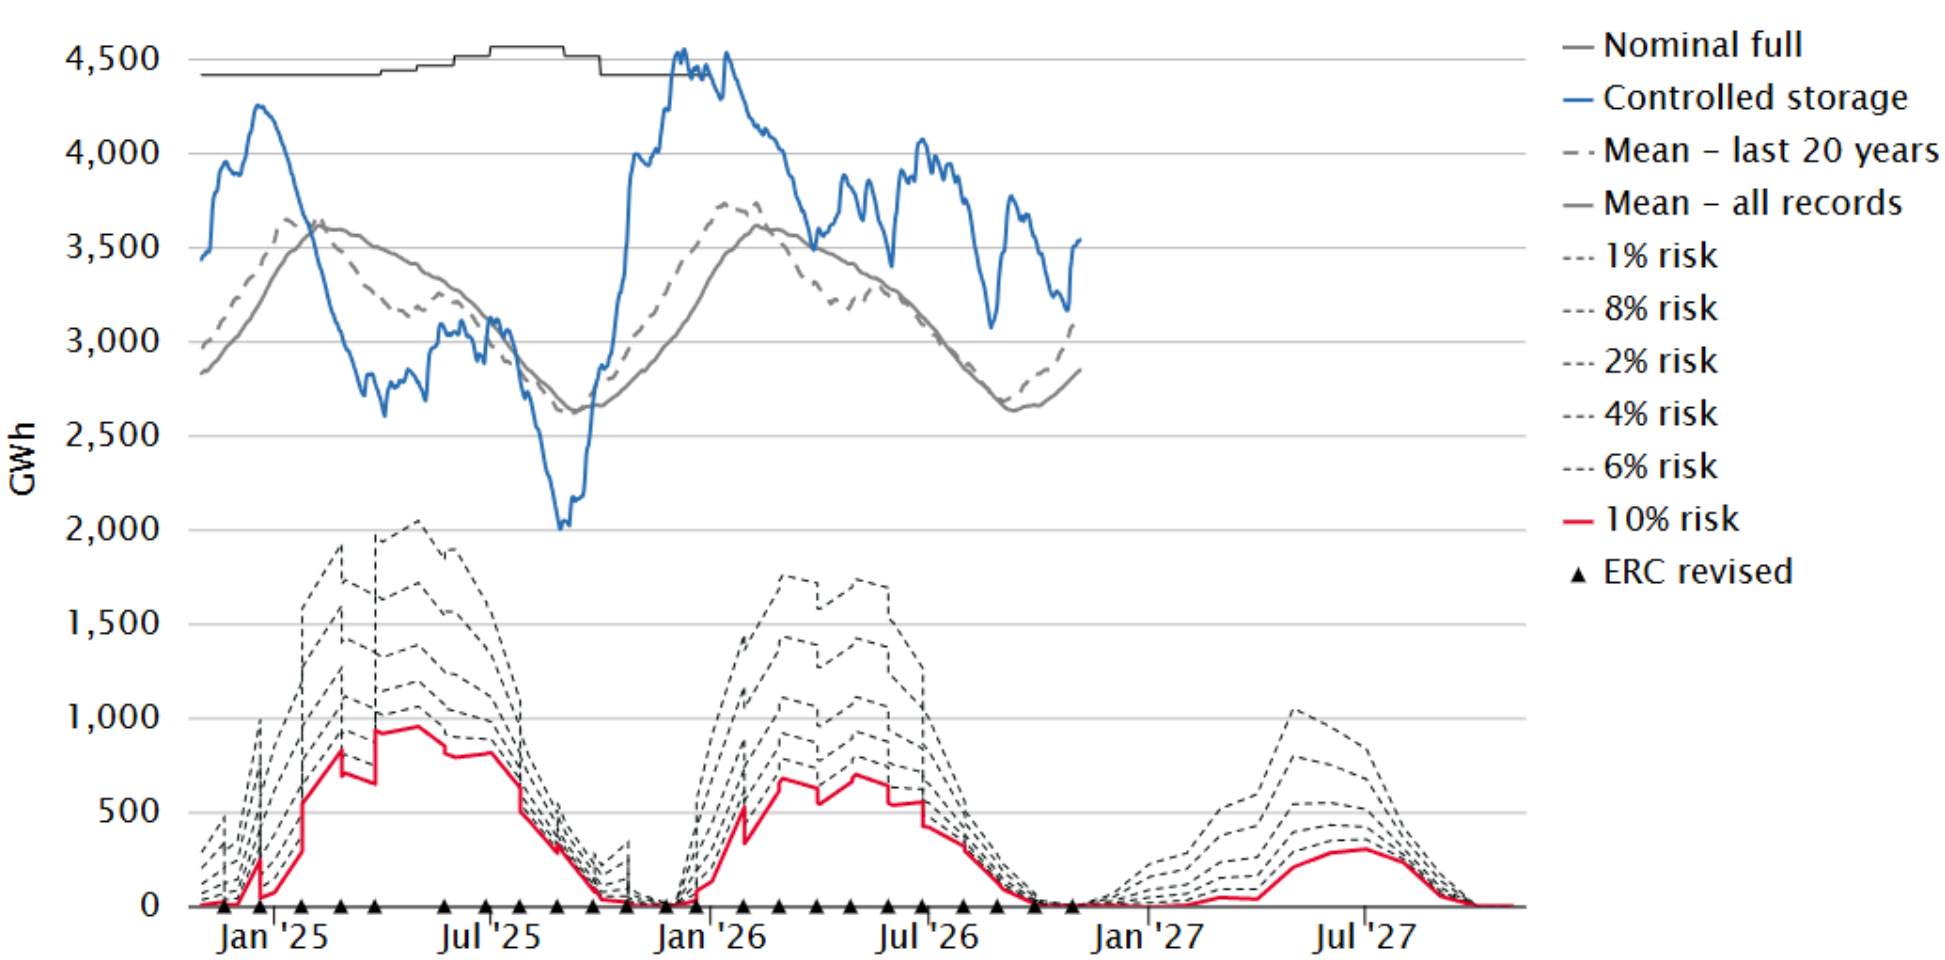
Storage fell steadily through most of October before high SI inflows at the end of the month resulted in storage ending the month close to where it started. Overall hydro storage decreased by 33 GWh during October, ending the month at 3,507 GWh, or 80% full. Storage remains well above the average level for this time of year. The following chart shows the latest breakdown of storage across the main hydro catchments.

Security of supply risks remained low in October, with storage levels well above average, as shown below.
Snowpack
Snowpack is an important form of stored hydro energy during winter and is released as inflows during spring. The following graph shows that the snowpack in the important Waitaki catchment decreased during much of October before increasing at the end of the month. It is now close to the mean for this time of year, based on observations from the past 30 years.

Climate outlook overview September - November 2025 (from NIWA)
- Very strong El Niño conditions are firmly established in the tropical Pacific and have intensified further in October. Forecasts indicate the event may reach its peak during the outlook period (November 2026 to January 2027). As a result, El Niño is expected to remain the primary driver of New Zealand's climate patterns over the coming three months.
- A westerly-quarter circulation pattern is expected to prevail for much of the season, consistent with the influence of a very strong El Niño. Higher than normal pressure is favoured to the north of New Zealand and lower than normal pressure to the south.
- A mix of northwesterly, westerly, and southwesterly airflows is expected during the season, with periodic low-pressure systems bringing more active and unsettled weather, particularly to the South Island.
- Despite some uncertainty in the balance of these circulation patterns, all forecast scenarios favour enhanced westerly-quarter flow overall. As a result, confidence is relatively high for a drier-than-normal season in the east of the North Island and a wetter-than-normal season in the far south and west of the South Island.
- Temperatures for November 2026 to January 2027 are most likely to be above average across the North Island and the east of the South Island. Near average or above average temperatures are forecast for the north of the South Island, while near average temperatures are most likely in the west of the South Island. Temperatures are expected to be more variable than usual, with periods of warmth interspersed with cooler spells. Spells of unusually high temperatures are expected to be most frequent and intense on the eastern sides of both islands.
- Rainfall totals for November 2026 to January 2027 are most likely to be below normal in the north and east of the North Island and above normal in the west of the South Island. Confidence is relatively high in these outcomes, particularly for the dry signal in the east of the North Island and the wet signal in the southwest of the South Island, which are supported across most forecast scenarios. In the east of the South Island, near normal or below normal rainfall totals are about equally likely. Near normal rainfall is most likely in the west of the North Island and the north of the South Island. However, forecast probabilities are more evenly distributed in these two regions, reflecting greater uncertainty in the seasonal rainfall outcome.
- Soil moisture, river flows, and lake storage levels remain generally healthy across the South Island, although conditions have become somewhat drier in some regions and snow storage has recently dropped below typical levels for the time of year. In contrast, below normal soil moisture and river flows are evident across parts of the North Island. The east and north of the North Island are particularly likely to experience reduced rainfall, more frequent dry spells, and continued drying of soils and vegetation, likely creating challenges for water-dependent sectors.
- Soil moisture levels and river flows are most likely to be below normal in the east and north of the North Island, while near normal or above normal conditions are favoured in the west of the South Island. Near normal or below normal soil moisture levels and river flows are expected for the remaining regions of New Zealand.
- The Relative Oceanic Niño Index (RONI) has already surpassed the peak values recorded during the 1997/98 El Niño and is rapidly approaching the maximum reached during the 2015/16 event, despite those events not reaching their peak intensity until much later in the year. Coupled with the unprecedented rate of warming observed since January 2026, this suggests the current El Niño is likely to rank among the strongest on record and may ultimately become the strongest observed in the instrumental era.
- The outlook period (November 2026-January 2027) coincides with the beginning of the Southwest Pacific tropical cyclone season. The Southwest Pacific Tropical Cyclone Outlook indicates normal to above normal tropical cyclone activity for the basin as a whole, while the risk for northern New Zealand is considered near normal. Historically, strong El Niño events tend to shift tropical cyclone activity eastward across the Southwest Pacific, increasing activity in the central and eastern parts of the basin relative to normal.

The Wholesale Gas Market
Spot gas prices decreased through October. Prices for the month averaged $11.9/GJ – a 24% decrease compared to September. Average prices are 4% below what they were at the same time last year. Spot gas prices include the cost of carbon, which is currently around $2/GJ.

On the supply side, most fields declined in output slightly throughout October. Turangi /Kowhai was the exception, with production maintaining the average of 46 TJ/day from last month. McKee/Mangahewa fell slightly, averaging 64 TJ/day. Pohokura also fell to 20 TJ/day, while Maui averaged 32 TJ/day. Kupe maintained output of 30 TJ/day.
The following graph shows production levels from major fields over the last 7 years.

On the demand side, Huntly reduced its gas consumption during the month, averaging 5 TJ/day. Methanex maintained usage at close to 70 TJ/day through October. Ballance started the month using close to 15 TJ/day, increasing to about 20 TJ/day late in the month and staying at that level.
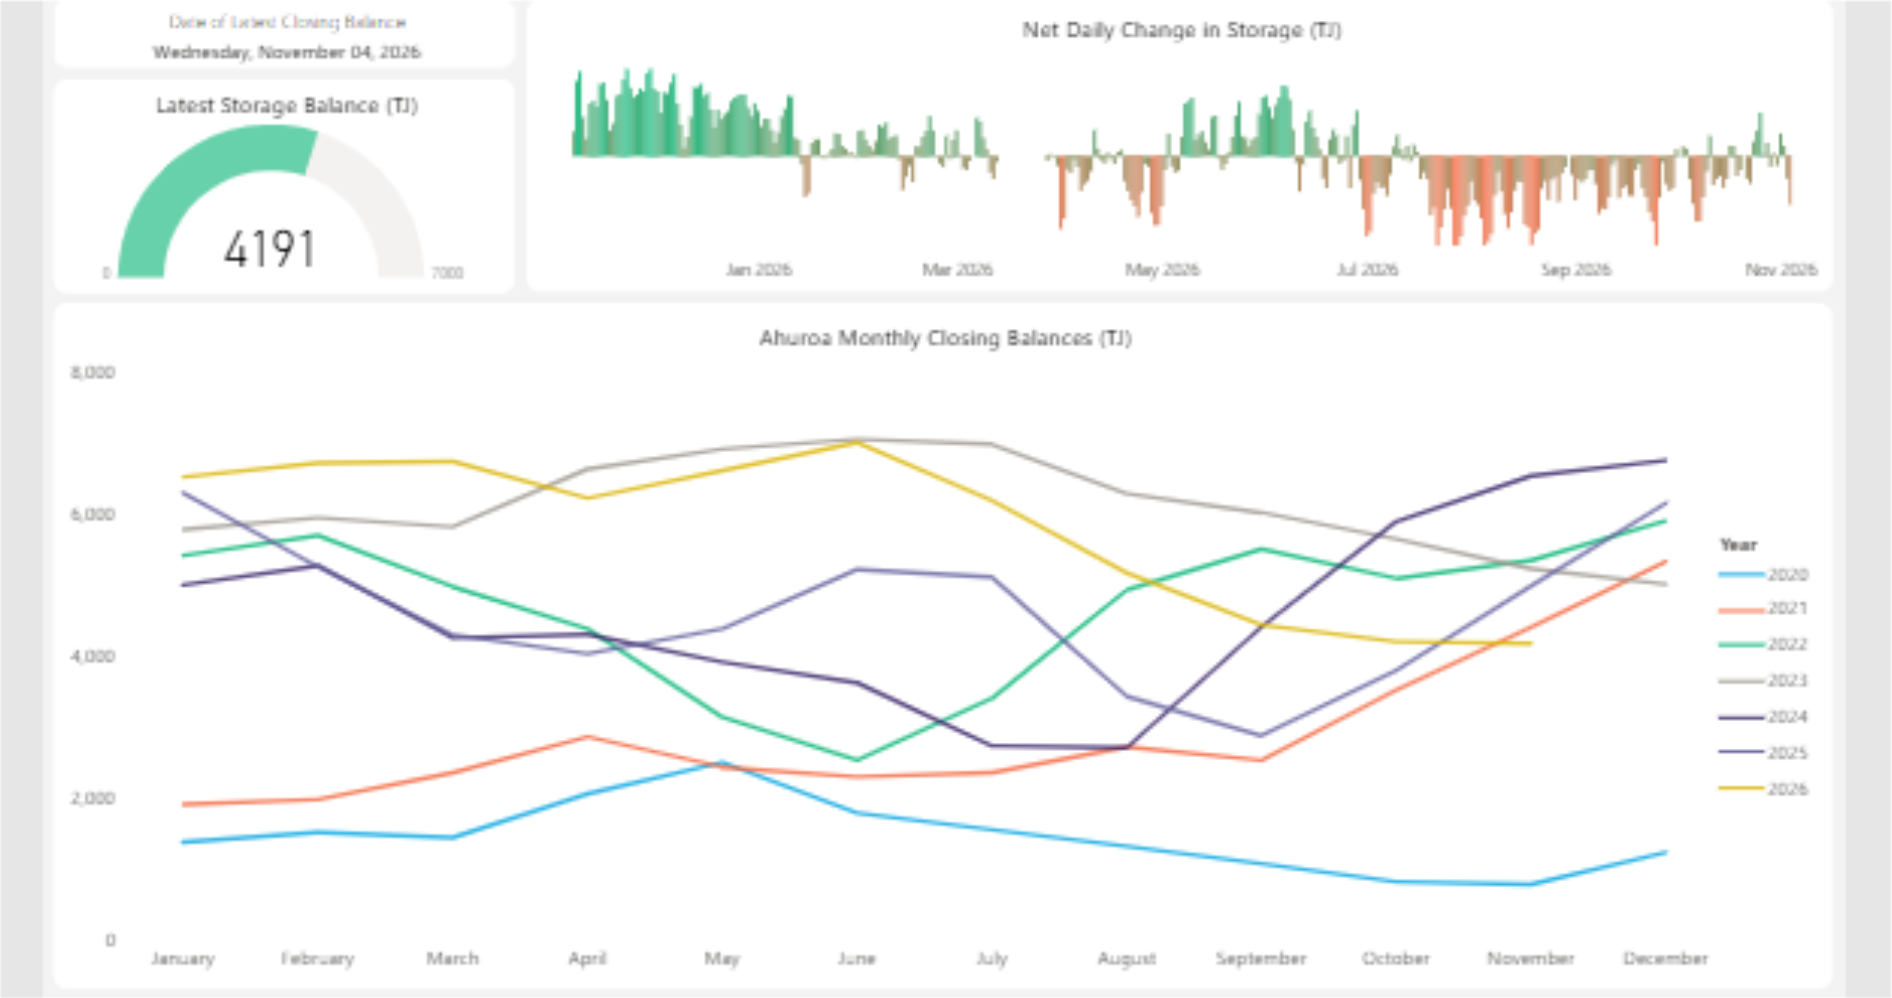
Gas storage is becoming increasingly important as falling production coincides with more variable demand, particularly from gas-fired electricity generation. The following chart shows how storage at Ahuroa decreased again in October but remains close to average levels seen at this time of year over the last few years.
International LNG netback prices have increased because of the conflict in the Middle East. Prices in October increased another 8% to $32.59/GJ. Forecast average prices are currently $22.83/GJ for 2026 and $33.59/GJ for 2027. (Note that netback prices are indicative of international prices, they are produced by the ACCC and quoted in Australian dollars. They are net of the estimated cost of converting pipeline gas in Australia to LNG, hence the term ‘netback’)

New Zealand does not yet have an LNG import or export market, so our domestic prices are not directly linked to global prices, though this may change following the Government's announcement that an LNG import terminal will be built in the next few years.
LPG is an important fuel for many large energy users, particularly in areas where reticulated natural gas is not available. The contract price of LPG is typically set by international benchmarks such as the Saudi Aramco LPG prices, which are normally quoted in US dollars per metric tonne.
The following graph shows the Saudi Aramco LPG prices for the last five years as well as forecast pricing for the year and a half ahead. The conflict in the Middle East caused prices to spike from April to June but they fell steeply in July before rising again recently. Futures prices increased through October.

The other main contributing factor to LPG prices in New Zealand is the exchange rate against the USD. The exchange rate was around 0.56 at the start of the month, increased to above 0.57 in the middle of the month before falling to end close to where it started at 0.56. This remains below the average levels seen in recent years. The recent decreases would tend to push up LPG prices when quoted in NZD.

The Coal Market
The conflict in the Middle East has contributed to an increase in coal prices along with other international energy commodities. To date the impact has not been as great as that observed during the initial years of the Ukraine war. Prices remained relatively flat for most of October and ended the month at $150/tonne. The following graph shows prices over the past ten years.

Like gas prices, coal prices can flow through to the electricity market.
Carbon Pricing
New Zealand has operated an Emissions Trading Scheme since 2008. The NZ ETS is New Zealand’s primary policy tool for reducing greenhouse gas emissions and is established under the Climate Change Response Act 2002. Participants generally surrender one eligible emissions unit for each tonne of emissions for which they are liable. The principal domestic unit is the New Zealand Unit, or NZU.
The Government sets rolling five-year limits on the supply of NZUs, guided by New Zealand’s emissions budgets. These limits cover units supplied through government auctions and certain other channels, but do not limit all units entering the market, including NZUs issued for eligible emissions removals such as forestry. The Government also sets auction price controls, comprising an auction reserve price and a cost containment reserve trigger price. These controls apply to government auctions and are not absolute minimum or maximum prices in the secondary NZU market.
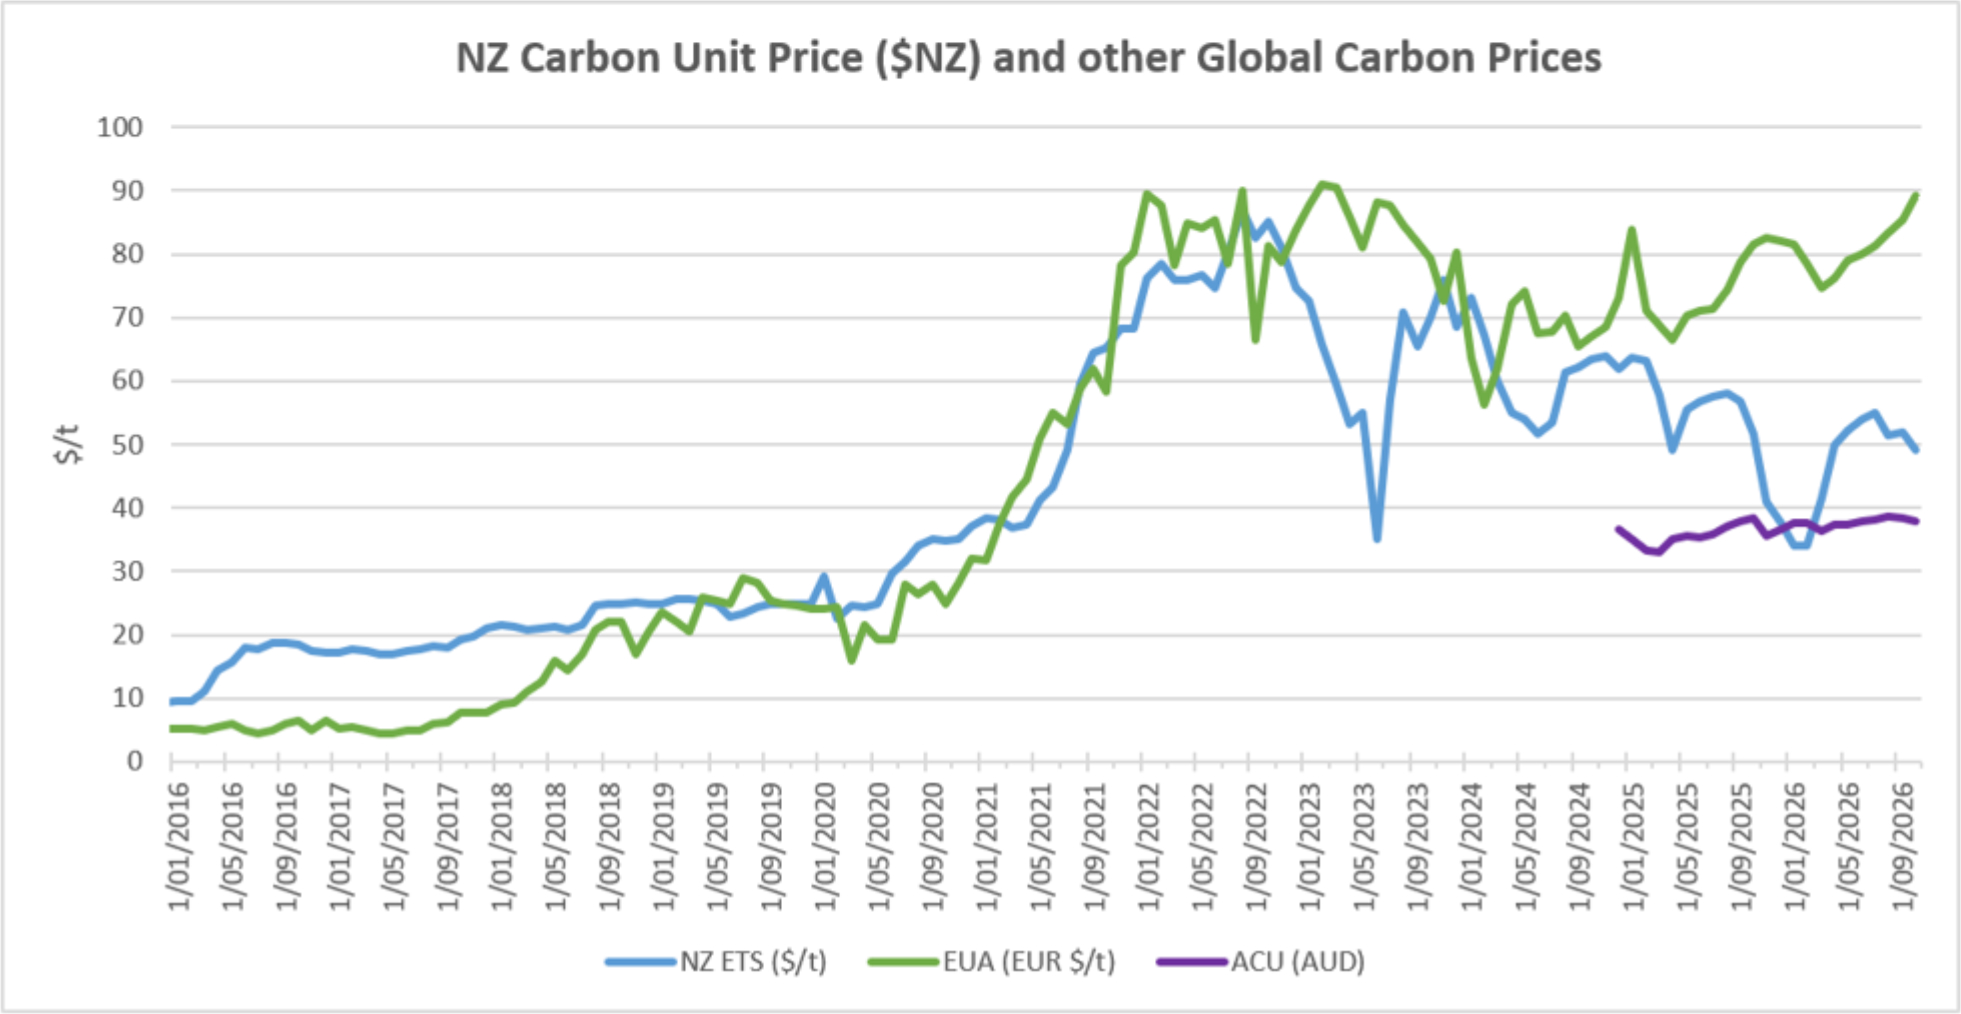
Secondary-market NZU prices decreased by 6% during October, ending the month at approximately $49 per unit.
A higher NZU price increases the effective cost of coal, natural gas and other fossil fuels used in process heat. It can also affect wholesale electricity prices when fossil-fuel generation is marginal. Hydro generators may also reflect the replacement value of stored water relative to thermal generation costs when making dispatch and contracting decisions.
At an NZU price of $50 per tonne of carbon dioxide equivalent, the direct carbon cost of coal- or gas-fired generation depends on the plant’s emissions intensity. A carbon-cost effect of approximately $25/MWh would correspond to an emissions intensity of about 0.5 tonnes of carbon dioxide equivalent per MWh. The actual wholesale-price effect varies with the marginal generator, fuel price, plant efficiency, hydro conditions and market conditions.
Over the longer term, higher carbon prices are intended to encourage investment in lower-emissions technologies and reduce reliance on fossil-fuel generation.
EU carbon allowances increased by 4% during October to €89.15 per tonne, while Australian Carbon Credit Units decreased by 1% to A$38.
About this Report:
This energy market summary report provides information on wholesale price trends within the NZ Electricity Market. Please note that all electricity prices are presented as a $ per MWh price and all carbon prices as a $ per unit price. All spot prices are published by the Electricity Authority. Futures contract prices are sourced from ASX.
Further information can be found at the locations noted below.
- Transpower publishes a range of detailed information, which can be found here: https://www.transpower.co.nz/power-system-live-data
- The Electricity Authority publishes a range of detailed information, which can be found here: https://www.emi.ea.govt.nz/
- Weather and Climate data – The MetService publishes a range of weather-related information, which can be found here: https://www.metservice.com/
Disclaimer: This document has been prepared for informational and explanatory purposes only and is not intended to be relied upon by any person. This document does not form part of any existing or future contract or agreement between us. We make no representation, assurance, or guarantee as to the accuracy of the information provided. To the maximum extent permitted by law, none of Smart Power Ltd, its related companies, directors, employees or agents accepts any liability for any loss arising from the use of this document or its contents or otherwise arising out of or in connection with it. You must not provide this document or any information contained in it to any third party without our prior consent.
About Smart Power:
Smart Power is a full-service Energy Management consultancy. Apart from Energy Procurement, Smart Power can also provide:
- Technical advice on how to reduce your energy use & emissions
- Sustainability Reporting
- Invoice Management Services
We also offer boutique energy and water billing services for landlords/property developers.
Contact us here or call one of our offices to talk to our experienced staff about how we can assist you with achieving your energy goals.
© Copyright, 2026. Smart Power Ltd


